Special report for Canadian investors, November 2026
The U.S. Buys Nearly Half Its Nickel From Canada And Cannot Smelt It. TSXV: FAN.V Found A Magnetic Nickel-Cobalt Alloy In Newfoundland That Skips The Smelter, And Is Beating Nickel And The Nickel Miners ETF (NIKL) In 2026.The U.S. Buys Nearly Half Its Nickel From Canada And Cannot Smelt It. TSXV: FAN.V Found A Magnetic Nickel-Cobalt Alloy That Skips The Smelter.
See how to invest in FAN →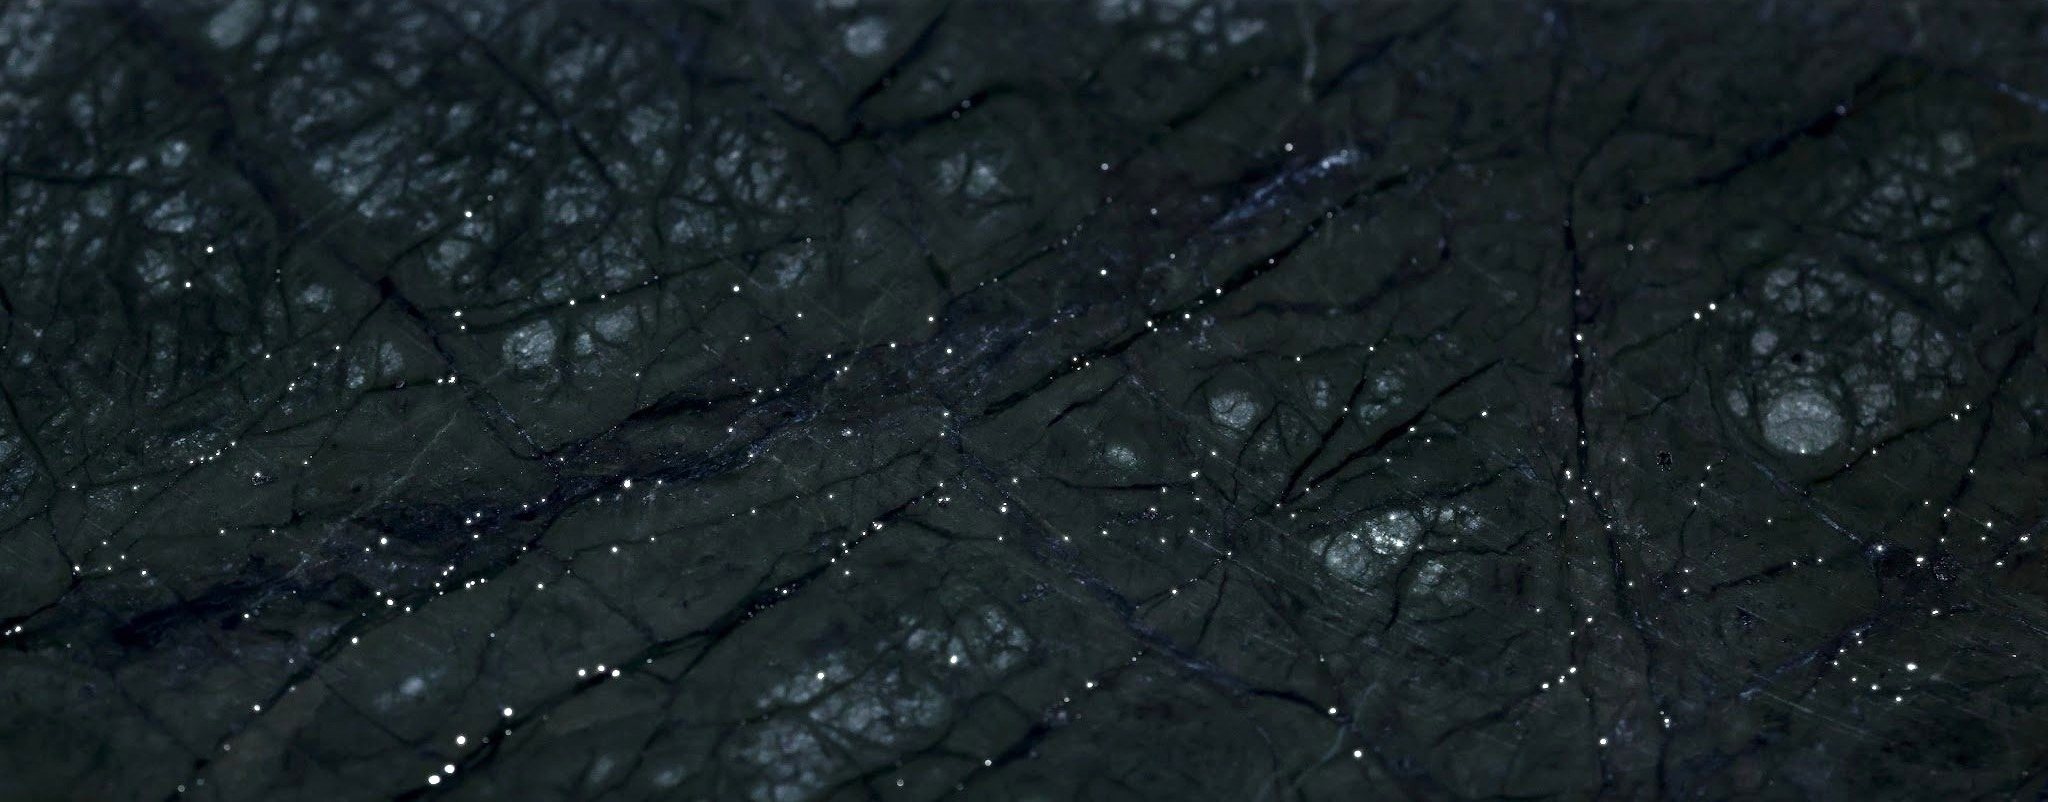
A rare magnetic
nickel-cobalt alloy.
No smelter needed.
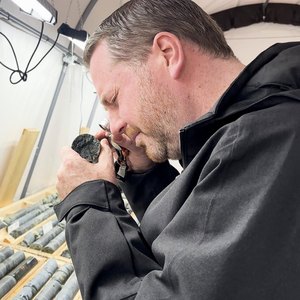
Canada mines nickel and ships it out of the country to be smelted and refined elsewhere.[1] First Atlantic Nickel & Cobalt Corp. (TSX-V: FAN, OTCQB: FANCF) owns 100% of Pipestone XL, a 30 km belt in central Newfoundland, where it found awaruite, a natural nickel-iron-cobalt alloy that magnets and flotation concentrate at the mine with no smelter: a 67.4% nickel, 1.76% cobalt concentrate from the RPM Zone, five zones along the belt, and two new 2026 discoveries, the Alloy Max North and Alloy Max South zones. While nickel and the Nickel Miners ETF fell in 2026, FAN shares rose,[2][3][4] and about $13.4 million raised since September, the latest placement at a 22% premium to market, funds drilling through 2027.[5]
Why Investors Are Watching FAN: A Rare, Large-Scale Magnetic Nickel-Cobalt Alloy Discovery That Bypasses the Smelting Bottleneck and Could Feed Canadian Stainless Steel, Aerospace Alloy and Battery Material Plants Directly
First Atlantic Nickel & Cobalt owns 100% of the Pipestone XL Nickel-Cobalt Alloy Project, a 30 km belt in central Newfoundland, Canada, targeting awaruite (Ni3Fe), a rare, magnetic nickel-iron-cobalt alloy recovered with no smelter.[5]
One Year of Nation-Building: Looking Back, Moving Forward, keynote address
“We are now moving urgently to use these resources to create capacity to produce and process critical minerals domestically... When we put cards in our hand that others want, it gives us influence on the world stage and in trade negotiations.”[6]
Canada ships its nickel away, and the value goes with it. Of about 125,000 tonnes mined in 2024, Canada exported 98,000 tonnes unwrought.[1] Glencore’s Sudbury matte is refined in Norway,[7] Vale closed Thompson in 2018,[8] and refined output has fallen 54% in a decade.[9] Canada’s largest bank put it in one phrase:[10]
Shaz Merwat, RBC Thought Leadership
“Canada remains largely a ‘mine-and-ship’ jurisdiction when it comes to critical minerals.”[10]
First Atlantic Nickel & Cobalt (TSX-V: FAN, OTCQB: FANCF) is the answer to both. Its Pipestone XL awaruite can be processed by magnetic separation and flotation into a pure nickel-cobalt alloy concentrate, with no smelter:[11] the cards Minister Hodgson wants in Canada’s hand, and the answer to RBC’s mine-and-ship.[6][10]
Key Investor Highlights
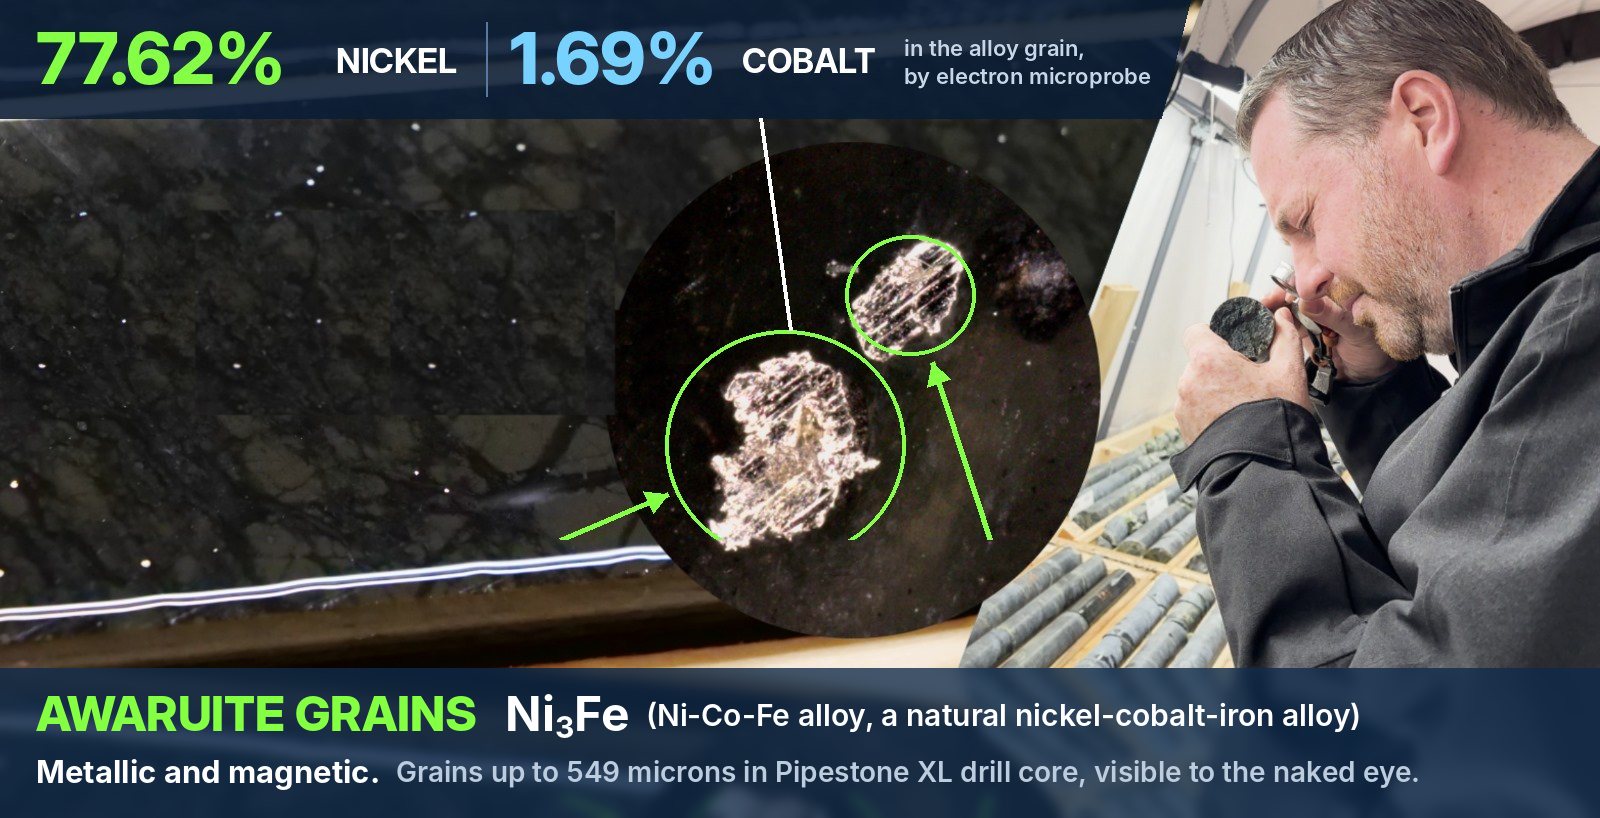
- Proven Mineralogy, 77.62% Nickel in the Alloy: SGS Canada microprobe analysis of RPM Zone awaruite returned 77.62% nickel and 1.69% cobalt, up to 86.68% nickel and 6.05% cobalt.[12]
- Proven Metallurgy, a Pure Alloy Concentrate: magnetic separation and flotation at SGS produced a concentrate averaging 67.4% nickel, up to 71.9% nickel, with 1.76% cobalt.[13]
- Already 5 Zones Across 30 km, Multi-Pit Potential: RPM, Super Gulp, Alloy Max North and Alloy Max South, all found by First Atlantic since 2024, plus the historic Atlantic Lake Zone.[14]
- Fully Funded for 2026 and 2027: about $13.4 million raised since September 2026 in three no-warrant private placements, the latest at a 22% premium to market.[5]
- Largest Nickel-Cobalt Alloy and Chromium Discovery in Atlantic Canada Since Voisey’s Bay: one of the largest nickel takeovers on record,[15] and the first such discovery in awaruite.[16][14]
- Two of Canada’s Six Priority Critical Minerals: nickel and cobalt share one alloy at Pipestone XL, with chromium, also a Canadian critical mineral, beside it.[17][18]
- No Tariffs on Nickel or Cobalt: Washington’s 50% tariffs on Canadian steel, aluminum and copper spare the two metals it lacks the ability to process, and Canada supplies 44% of its primary nickel imports.[19][20][21][22]
- Two-Year Federal Reviews and Canada’s Fastest Permits: Bill C-5 sets two-year federal reviews,[23][24] and Newfoundland and Labrador alone of 68 Fraser Institute jurisdictions processed 100% of permits within six months or less.[25]
How to invest in First Atlantic Nickel & Cobalt in Canada: look up FAN on the TSX Venture Exchange at your broker, add it to your watchlist and register below for news and investor updates by email and text.
Get FAN News and Investor Updates by Email and Text
Register once and every news release comes to you the day it is issued. You can stop the alerts at any time.
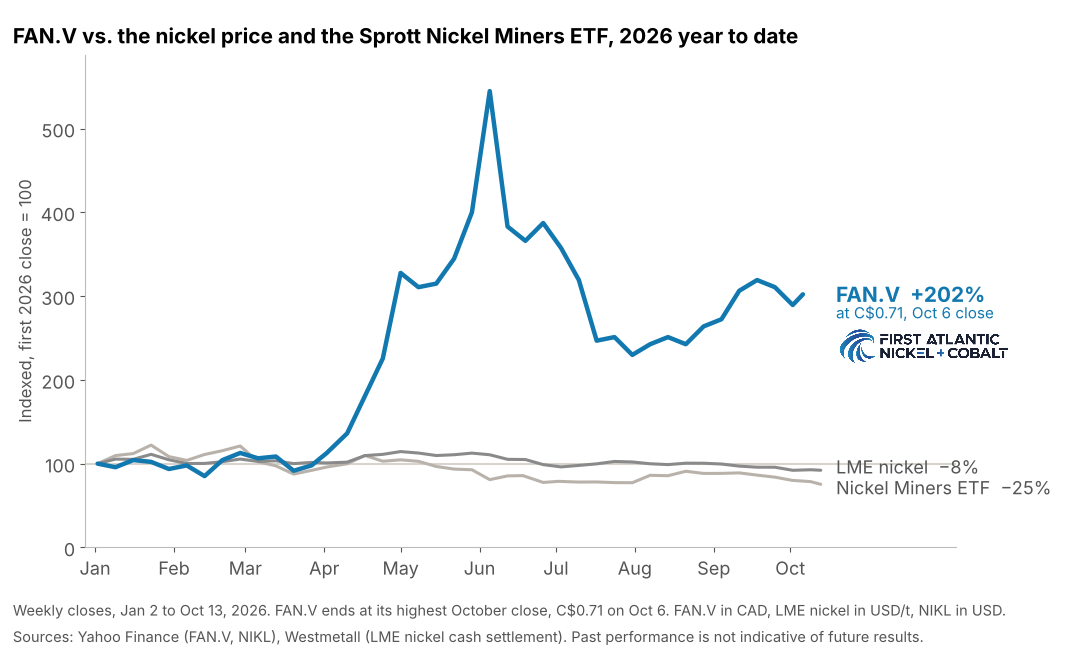
Follow Us on WhatsAppOfficial First Atlantic channel. One-way, your number stays private.In 2026 the nickel price fell[3] and the Sprott Nickel Miners ETF fell further,[4] while First Atlantic’s shares rose, up more than 200% at their highest October close.[2] The difference is the processing route and the 2026 results, not the metal price. Past performance is not indicative of future results.
+ More about this figure− Less
Nobody is building a new smelter, and the reason is not the geology. Canada has two aging nickel smelters left, both in Sudbury,[26] and no new one under construction.[27][28] Canada’s Energy Minister put it to the mining industry this way:
Canada’s Mining Moment: Prosperity, Security and Sustainability
“We are a top-five producer of key battery minerals, including nickel and cobalt, that underpin the transition to zero-emissions transportation... Moreover, as we all know, critical minerals also underpin defence systems and technologies, advanced computing, telecommunications and clean technologies... To put it simply, our critical minerals are crucial to our security, sovereignty and national defence.”[29]
First Atlantic Nickel & Cobalt (TSX-V: FAN, OTCQB: FANCF) offers a large-scale solution in Canada that needs no smelter at all. Its 67.4% nickel alloy concentrate could, the company believes, feed battery refining, stainless steel and specialty-alloy production built in Canada.[11]
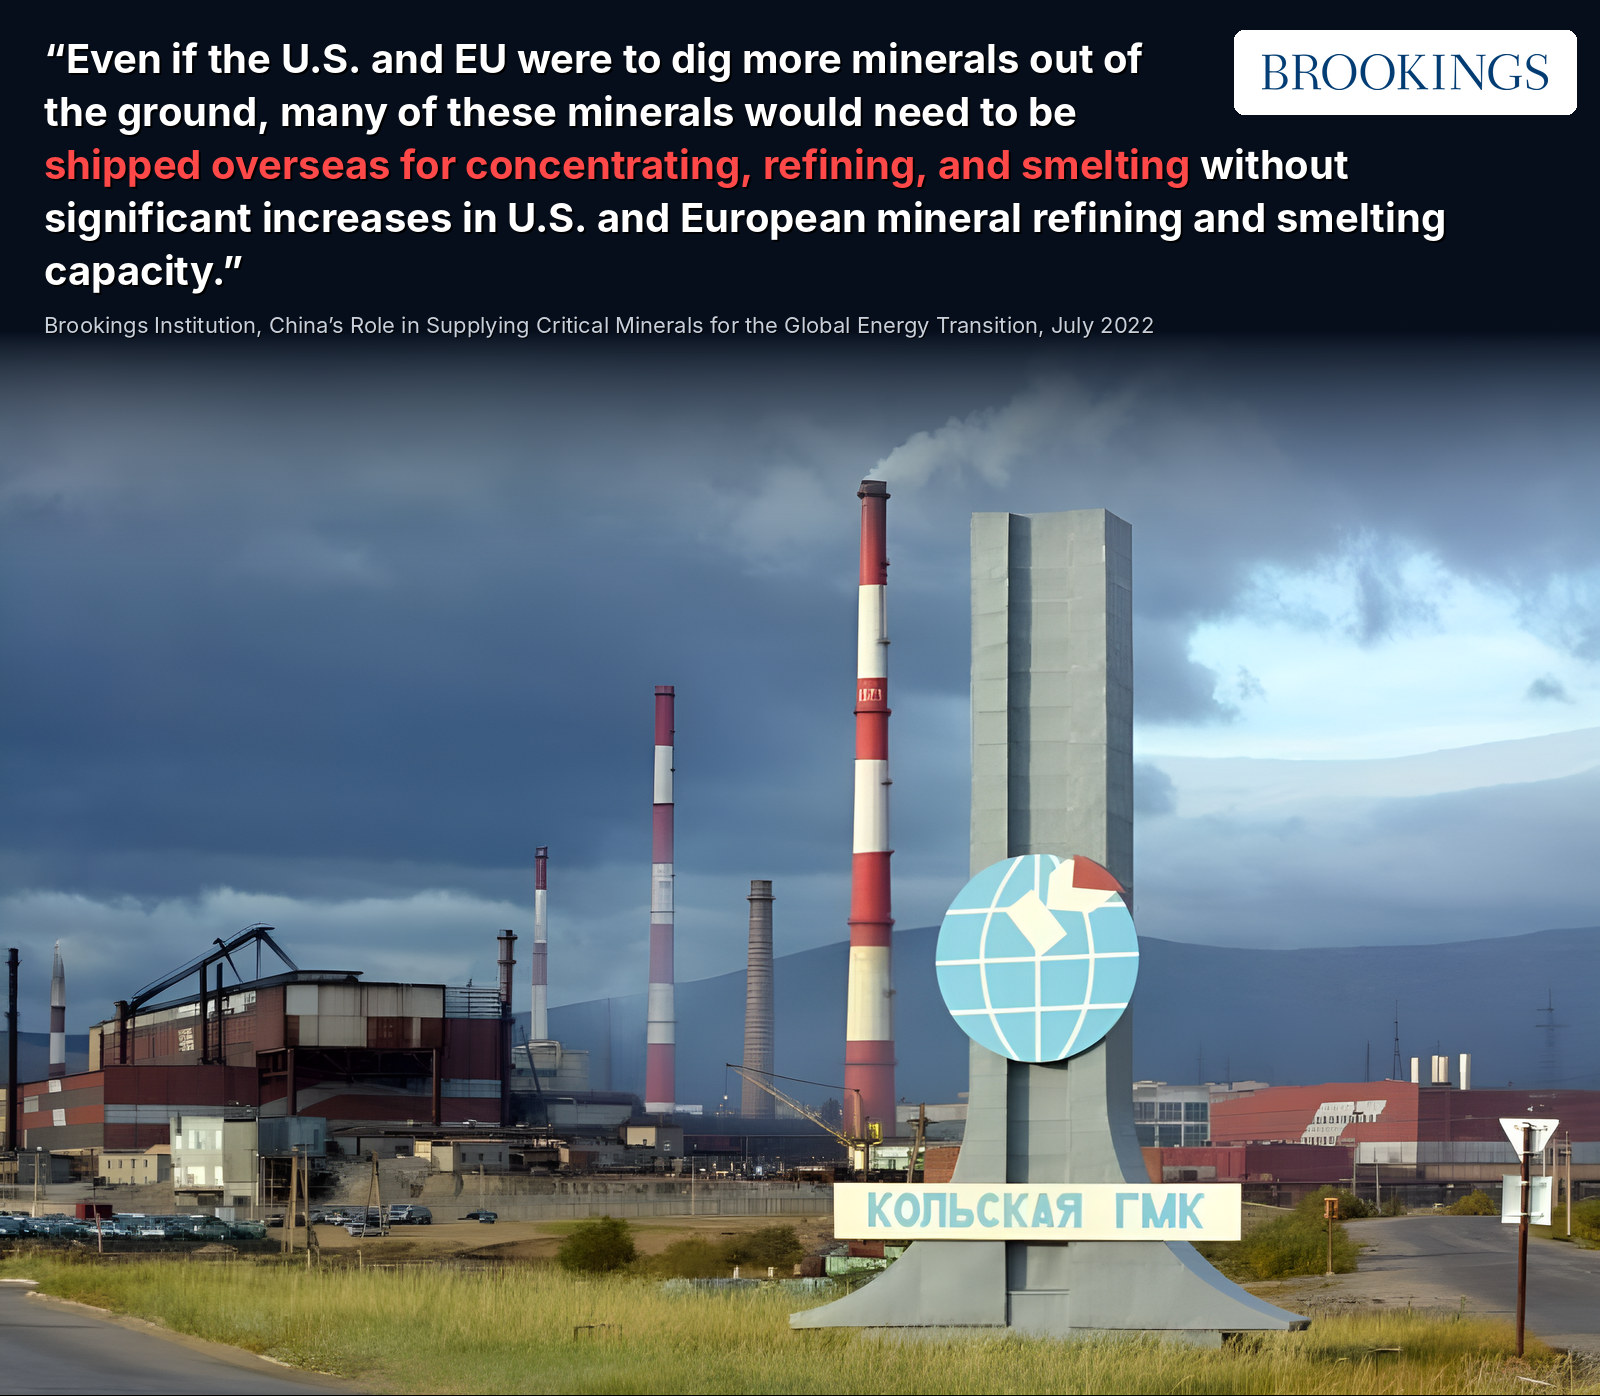
Allies from the G7[30] to Japan and Korea[31][32] want secure nickel and cobalt outside smelting controlled by China, Russia and Chinese-owned plants in Indonesia.
+ More about this figure− Less
Executive Director, Goodman School of Mines, Laurentian University
“The real strategic vulnerability today is not our geology; it is our processing capacity and supply chain dependence. In many cases, Canadian minerals are exported for refining and upgrading abroad before returning as inputs into advanced technologies.”[33]
Awaruite, the Rare Form of Nickel: A Naturally Magnetic Nickel-Iron-Cobalt Alloy Concentrated and Separated Without Smelting
Almost all nickel is sulfide or laterite ore: sulfide is smelted to burn off sulfur, releasing toxic SO2; laterite is leached with acid under high pressure. Both need costly plants hard to permit in North America.
Awaruite is a rare third form: nickel that nature has already turned into metal. Formed by serpentinization of ancient ocean mantle rock, awaruite (Ni3Fe) is naturally magnetic, recoverable with the magnetic separator drums used for a century on the Mesabi Iron Range and in Labrador’s iron mines.
“The development of awaruite deposits in other parts of Canada may help alleviate any prolonged shortage of nickel concentrate. Awaruite, a natural iron-nickel alloy, is much easier to concentrate than pentlandite, the principal sulfide of nickel.”[34]
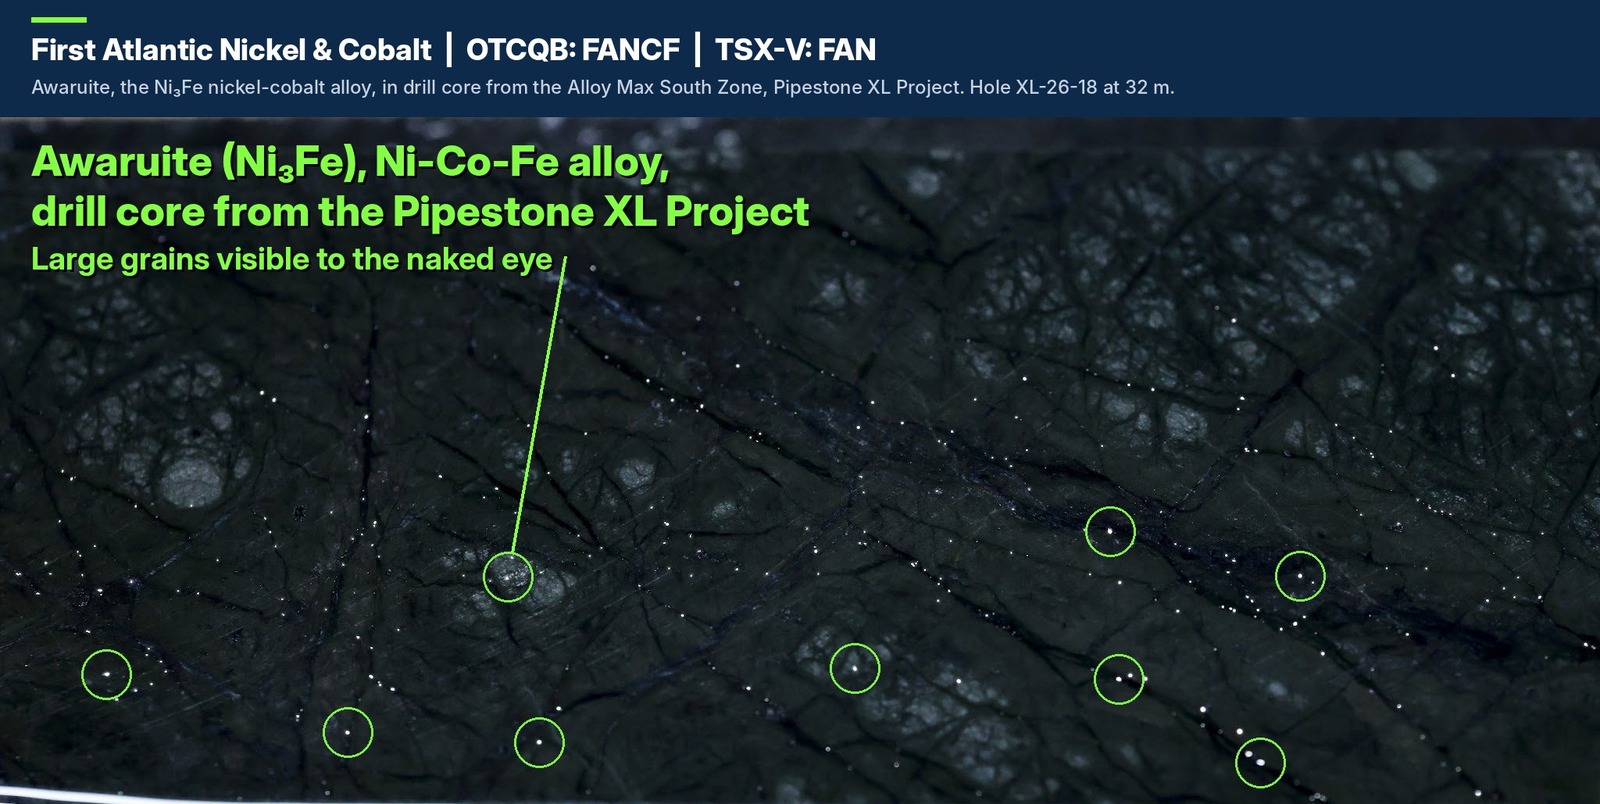
+ More about this figure− Less
First Atlantic has drilled the first major awaruite discovery since the USGS wrote that in 2012,[34] the largest in the Atlantic since Voisey’s Bay, acquired for $4.3 billion in 1996, more than $8 billion today.[15]
Cobalt travels inside the alloy, measured with the nickel in the same microprobe grains in May,[12] which is why the company became First Atlantic Nickel & Cobalt on April 29, 2026.[35]
Smelting is the step awaruite avoids. It is already metal, so it needs no plant costing billions of dollars and drawing hundreds of megawatts. Ontario’s business lobby said it plainly about the Ring of Fire:[36]
Uncovering the Economic Potential of Ontario’s Ring of Fire
“All agree that without government intervention, there is no business case to locate a chromite smelter in Ontario.”[36]
First Atlantic goes around that bottleneck: Pipestone XL rock can be concentrated at the mine with magnets and flotation and shipped to a North American refinery, with no smelter.[13]
Click the map for a larger, high-resolution view
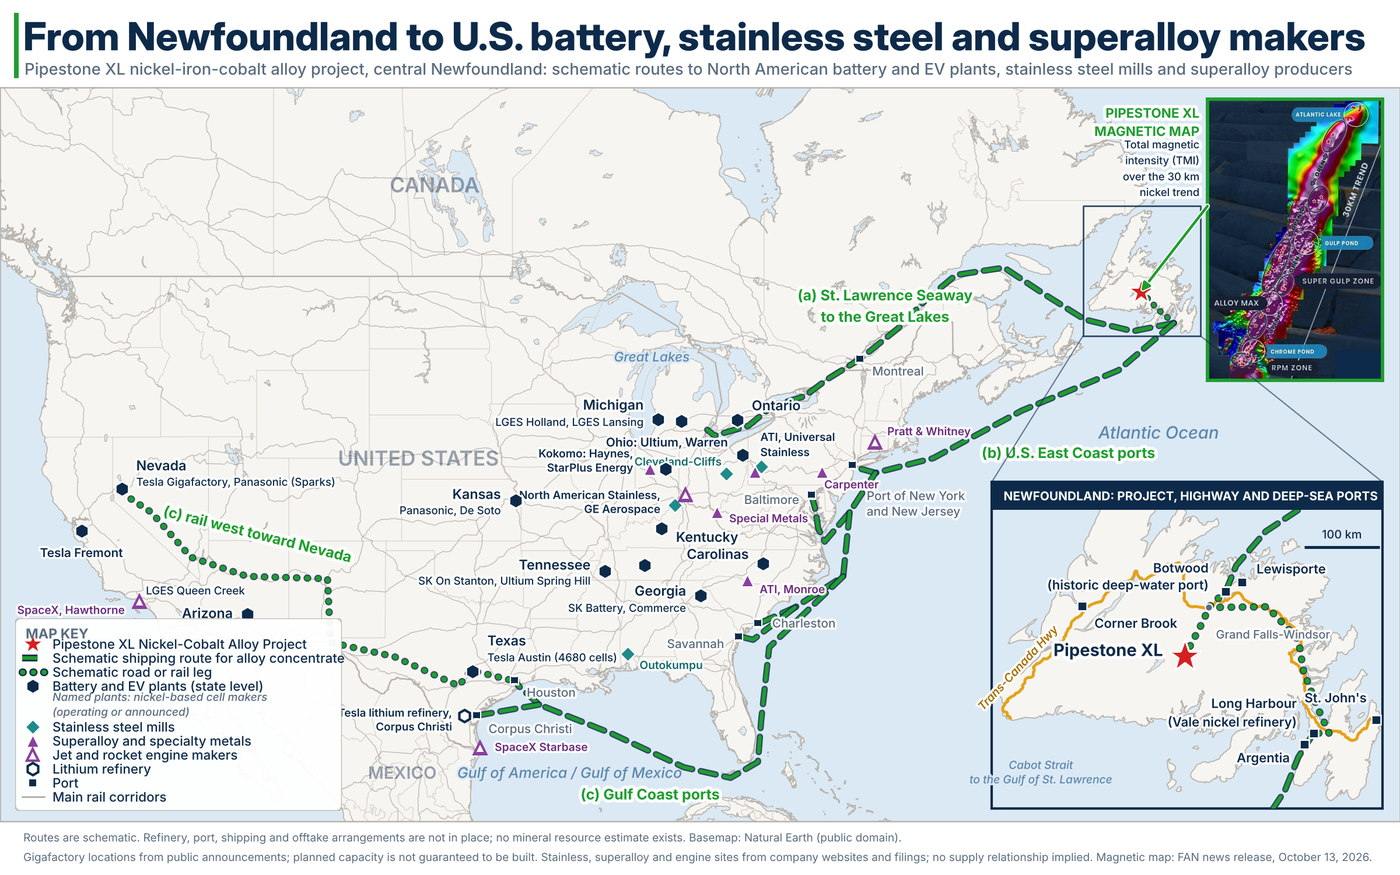
+ More about this figure− Less
No smelting saves billions in capital and cuts electricity demand. That means:
- Sulfur-free: the rock and its tailings are inert, with no risk of acid mine drainage.
- Lower electricity demand: magnets and flotation cells in place of a smelter or acid-leach autoclave.
- Easier, faster permitting: a safer process with a lower environmental footprint.
Washington is now writing the difference between ore and metal into law. The DOMINANCE Act, passed by the U.S. House in June 2026, defines processing as converting ore “into a metal, metal powder, or a master alloy.”[37] Awaruite is that metal alloy already.[38]
Senior Strategic Advisor, First Atlantic Nickel & Cobalt
Former Director, Office of Critical Minerals and Metals,
U.S. Department of Commerce
 FormerU.S. Department of Commerce
“The Company stands out in the global critical minerals sector with its large-scale discovery of awaruite (Ni3Fe) at its Pipestone XL Project in Newfoundland … processed onshore, directly at the mine site, using simple magnetic separation and flotation … a high-grade, environmentally responsible nickel-cobalt concentrate that can move directly into downstream stainless steel, specialty alloy, and battery refining … supplying the electric vehicle, energy storage, and defense sectors in the United States, Canada, the G7, and allied countries … the global critical minerals sector is dominated by a single country that is a non-market economy, and processing awaruite onshore bypasses the midstream smelting and processing constraints concentrated in that country.”[39]
+ Read the full quote− Back to the short version
“The Company stands out in the global critical minerals sector with its large-scale discovery of awaruite (Ni3Fe) at its Pipestone XL Project in Newfoundland, an exceptionally rare, naturally-occurring, magnetic, sulfur-free nickel-cobalt-iron alloy. This unique nickel-cobalt mineral can be processed onshore, directly at the mine site, using simple magnetic separation and flotation. The result is a high-grade, environmentally responsible nickel-cobalt concentrate that can move directly into downstream stainless steel, specialty alloy, and battery refining and manufacturing industries supplying the electric vehicle, energy storage, and defense sectors in the United States, Canada, the G7, and allied countries. This is significant because the global critical minerals sector is dominated by a single country that is a non-market economy, and processing awaruite onshore bypasses the midstream smelting and processing constraints concentrated in that country.”[39]
Click the map for a larger, high-resolution view
+ More about this figure− Less
Why Nobody Is Building a Nickel Smelter in Canada: Electricity, Emissions Rules, Billions in Capital and Treatment Charges Below Zero
Canada had three nickel smelters a decade ago and has two left, both in Sudbury and both decades old.[8][40] Most of its nickel leaves unwrought, 43% to the United States,[1][22] its last new nickel plant was the Long Harbour refinery in 2014,[27] and no new nickel smelter or refinery is under construction, or permitted and funded, anywhere in Canada,[28] though the Mining Association of Canada’s Brendan Marshall wrote that for Canada to keep its share of world nickel production, “seven new mines, two smelters and one refinery will need to come on line domestically in the next 30 years.”[42] There are four reasons.
Electricity. A smelter is one of the biggest customers on any grid, and with AI data centres pushing demand, grids are being stretched to their limits and power prices are rising across North America. In 2011 Cliffs said “there isn’t a location in Ontario that is economically viable” at current power rates for its Ring of Fire smelter,[43] and walked away in 2013.[44][45] Noront warned its ore “will get processed overseas... China would be the most obvious,”[46] and its $1 billion Sault Ste. Marie plant was never built.[47] Now data centres have their own Ontario rate class,[48] Hydro-Québec says Quebec “no longer has an energy surplus,”[49] and the U.S. Hawesville aluminum smelter closed in 2026 citing “fierce competition with Big Tech for competitively priced power.”[50]
Where Are We Now? A Report Card on the Ring of Fire
“Given current electricity rates, there is no business case to locate a ferrochrome smelter or stainless steel plant in the province... even with reduced electricity prices, the process of ferrochrome smelting is still prohibitively expensive, given its electricity-intensive nature.”[51]
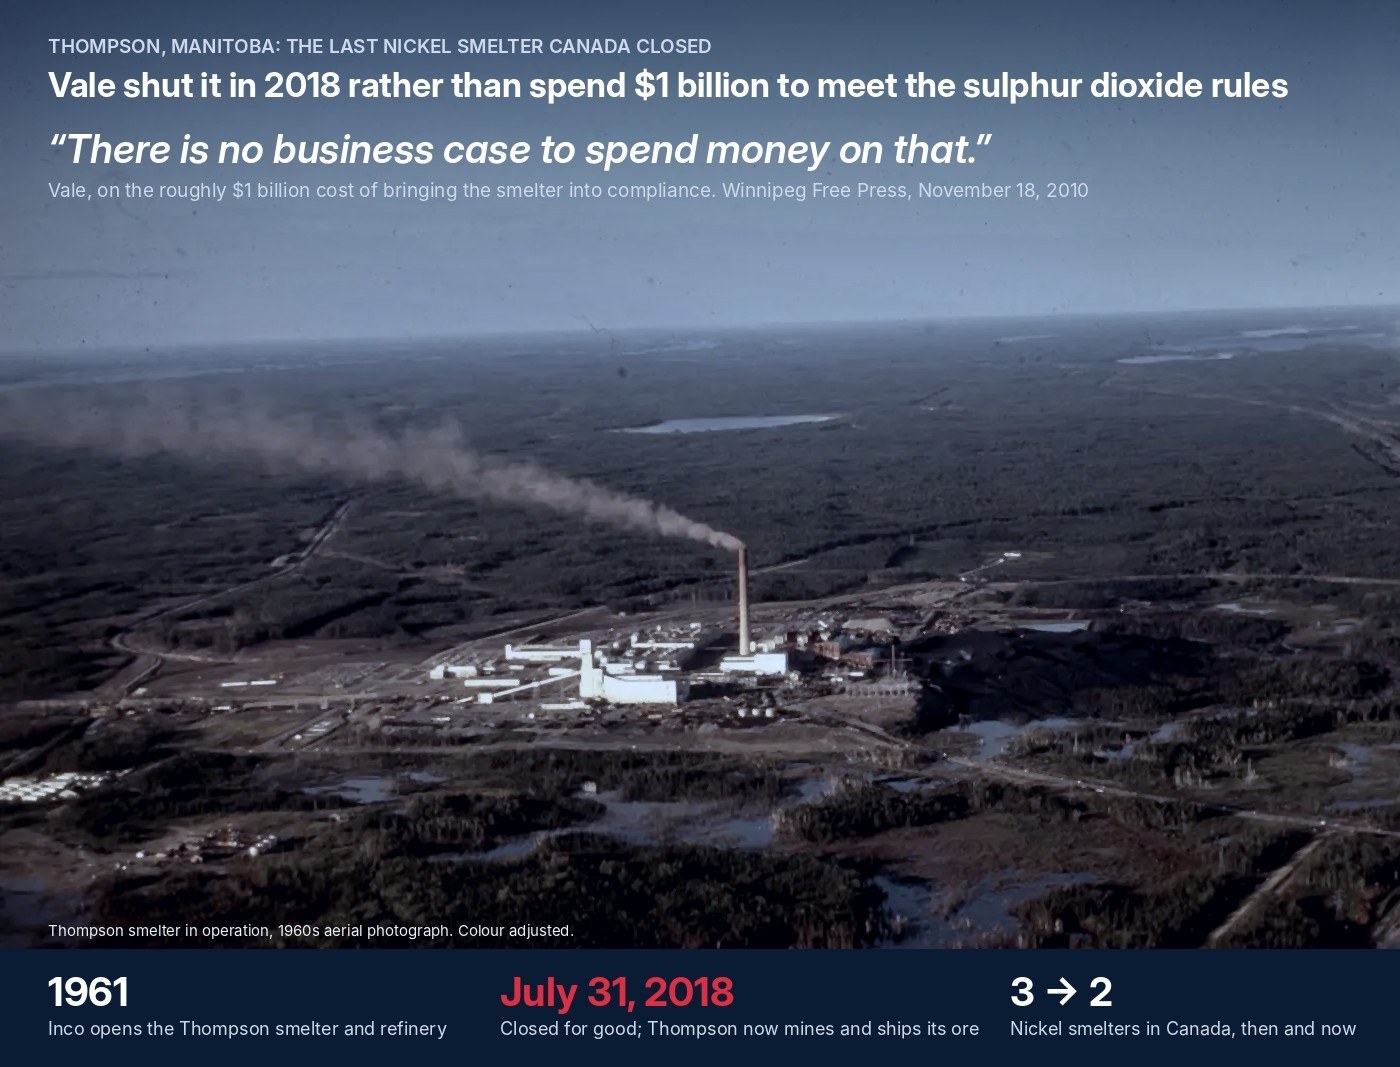
Emissions rules. The two smelters Canada has could not meet the law, so the law was changed for them. Under Ontario’s 2023 sulphur dioxide standard,[52] Vale reported “neither the Smelter nor the Nickel Refinery could meet the new standard,”[53] and Ontario exempted both,[54] after Vale and Glencore had spent more than a billion dollars cutting Sudbury emissions.[55][56] A new smelter would have to capture nearly all its sulphur from day one.[57] Facing a $1 billion bill to comply at Thompson, Vale shut it.[58][40]
+ More about this figure− Less
Capital and margins. A smelter costs billions on top of the mine, for a service China now prices at zero. Cliffs put its Ring of Fire smelter at $1.8 billion against about $150 million for the mine.[59] Canada Nickel’s roughly $1 billion Timmins plant looks to government for “the bulk of the funding.”[28] RBC: “Competing head-to-head in pure-play downstream processing against subsidized overcapacity is economically difficult.”[10] The Mining Association of Canada told the Commons defence committee why.
Vice-President, Economic Affairs and Climate Change, Mining Association of Canada
“The business case is certainly not there, currently, to expand our processing and smelting facilities... In some cases, the treatment and refining charges are below zero. There are negative numbers right now.”[60]
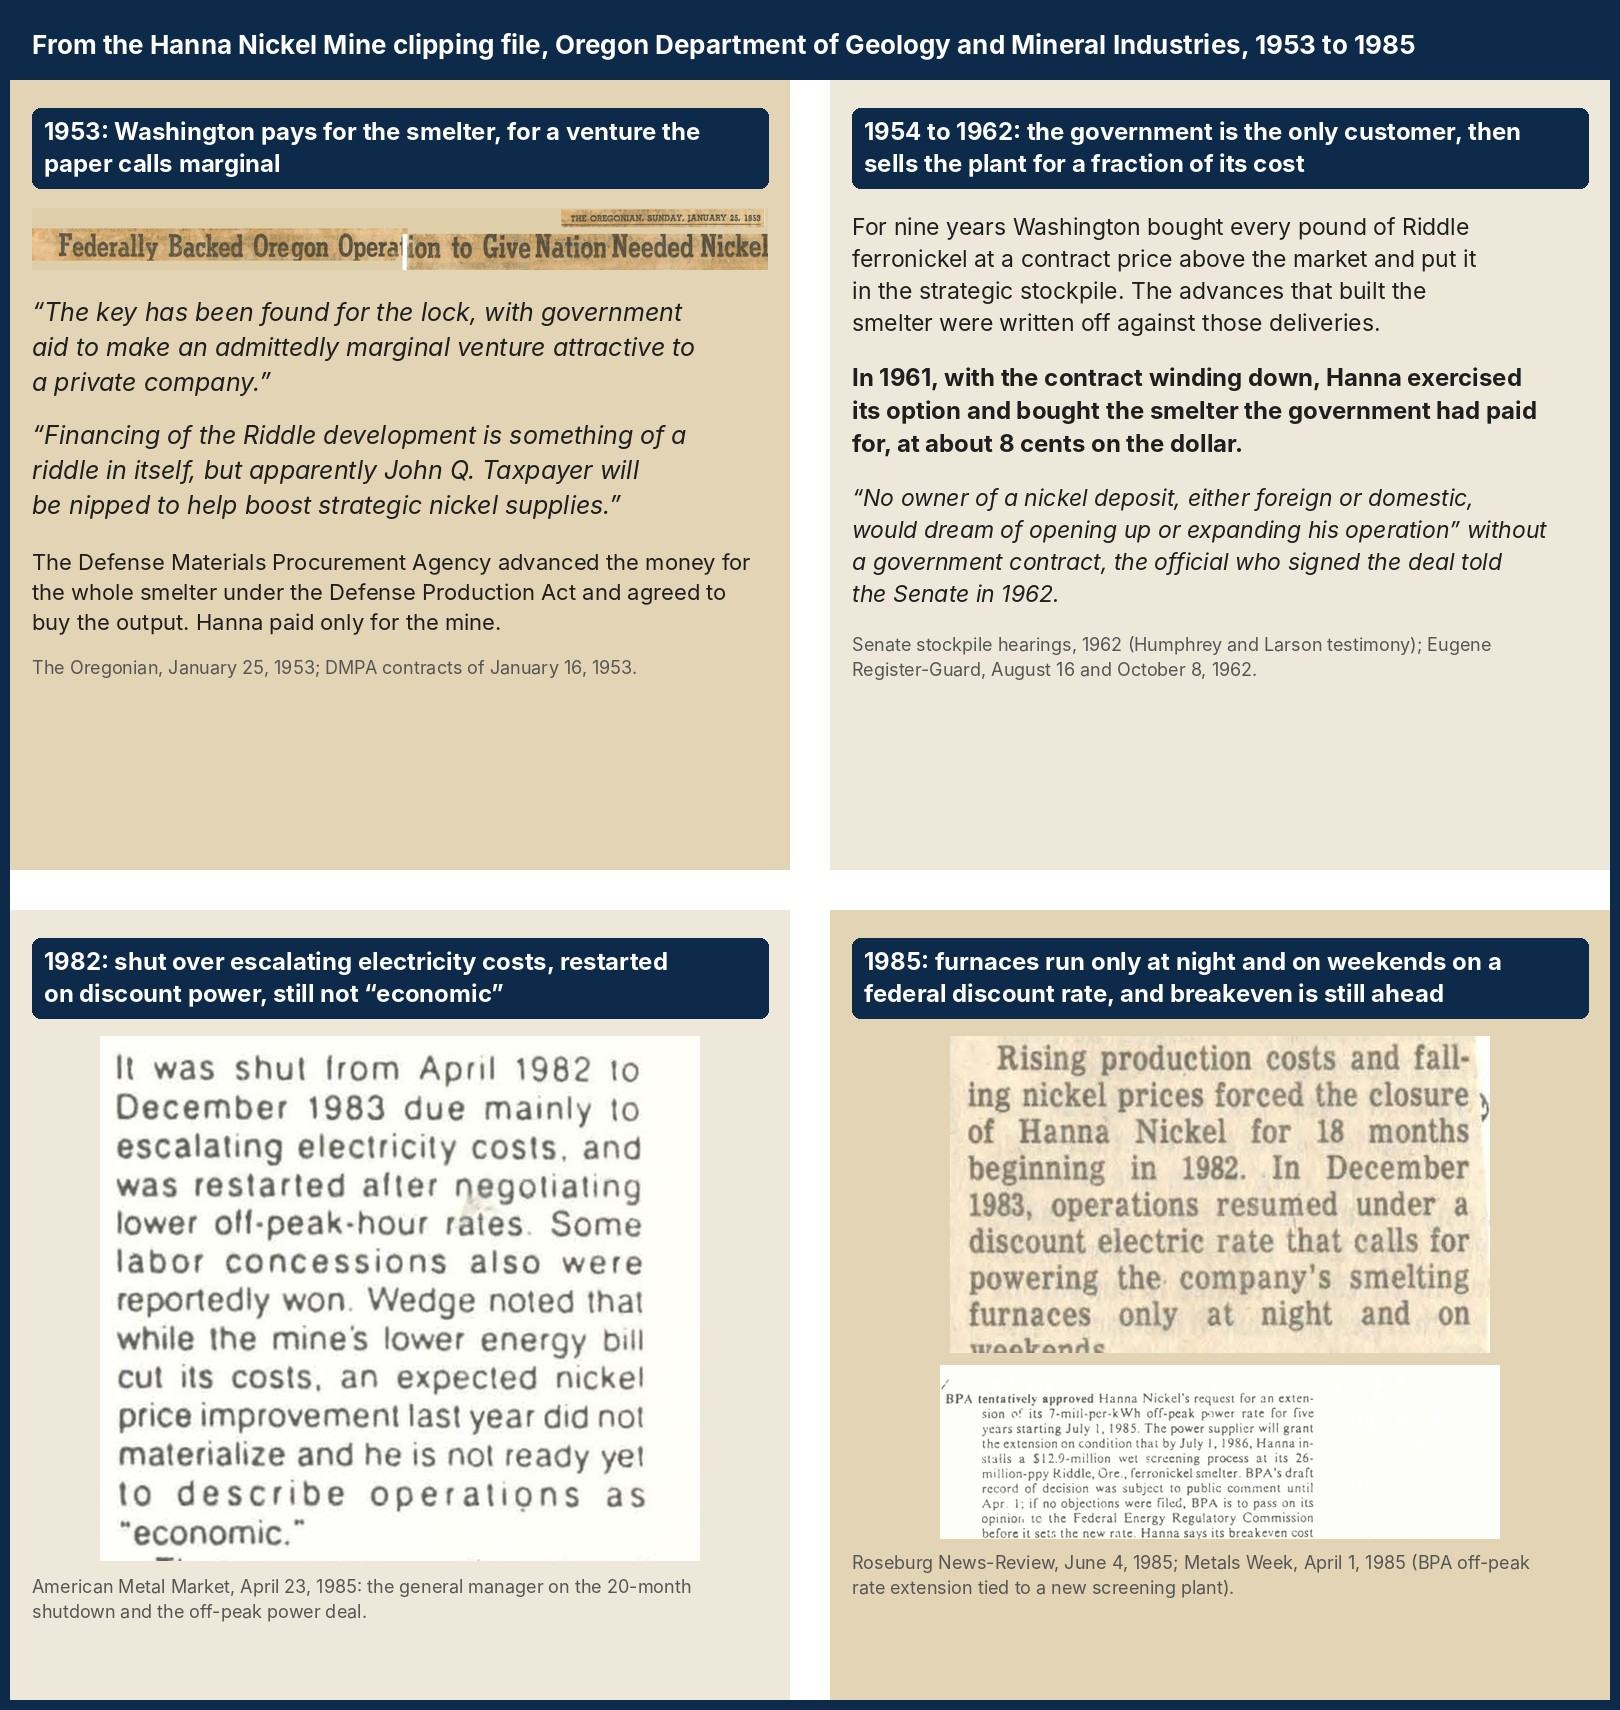
The one country that tried to subsidize its way to a nickel smelter is next door. The only U.S. nickel smelter, at Riddle, Oregon, was built in 1953 and 1954 almost entirely with federal money, which bought its nickel above the market price for nine years.[61] It shut in 1982 over electricity costs, reopened only on a 60% discount on off-peak federal power, still cost more per pound than nickel sold for,[61][62][63][64] and closed for good in 1998.[65] Washington is repeating the model for Korea Zinc’s Project Crucible in Tennessee, but not for nickel.[66][67][68] Figure 7 shows the Oregon record in the newspapers of the day; click it to read the clippings at full size.
Click the figure to read the clippings at full size
+ More about this figure− Less
A smelter that is not economic does not fix the problem, and Pipestone XL does not need one. Its 67.4% nickel alloy concentrate can go straight to refining in Canada or allied G7 and NATO industry:[11] no furnace, no acid plant, no sulphur dioxide.
Vice President, Corporate Affairs, Vale Base Metals
“Canada is the only country that can reliably supply both the CAF and NATO with both nickel and cobalt, from mining to refining, inside a trusted, geopolitically aligned jurisdiction.”[72]
ONSHORE MAX™: Magnetic Separation and Flotation Turn Pipestone XL Awaruite Into a 67.4% Nickel Alloy Concentrate
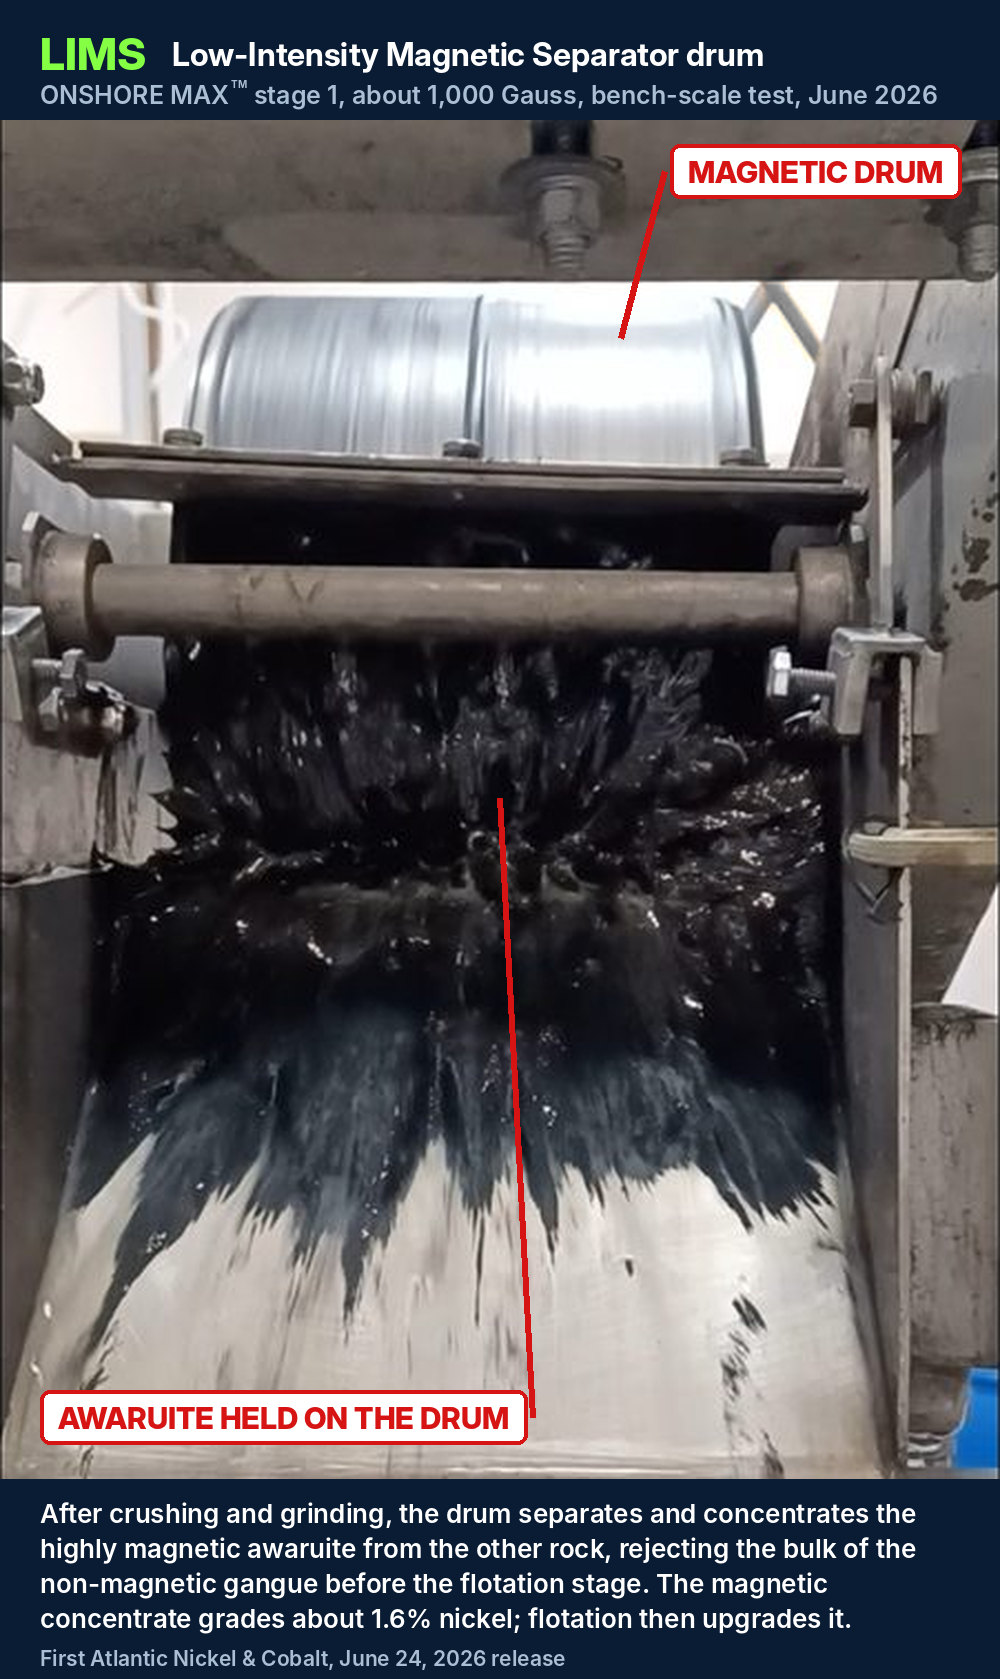
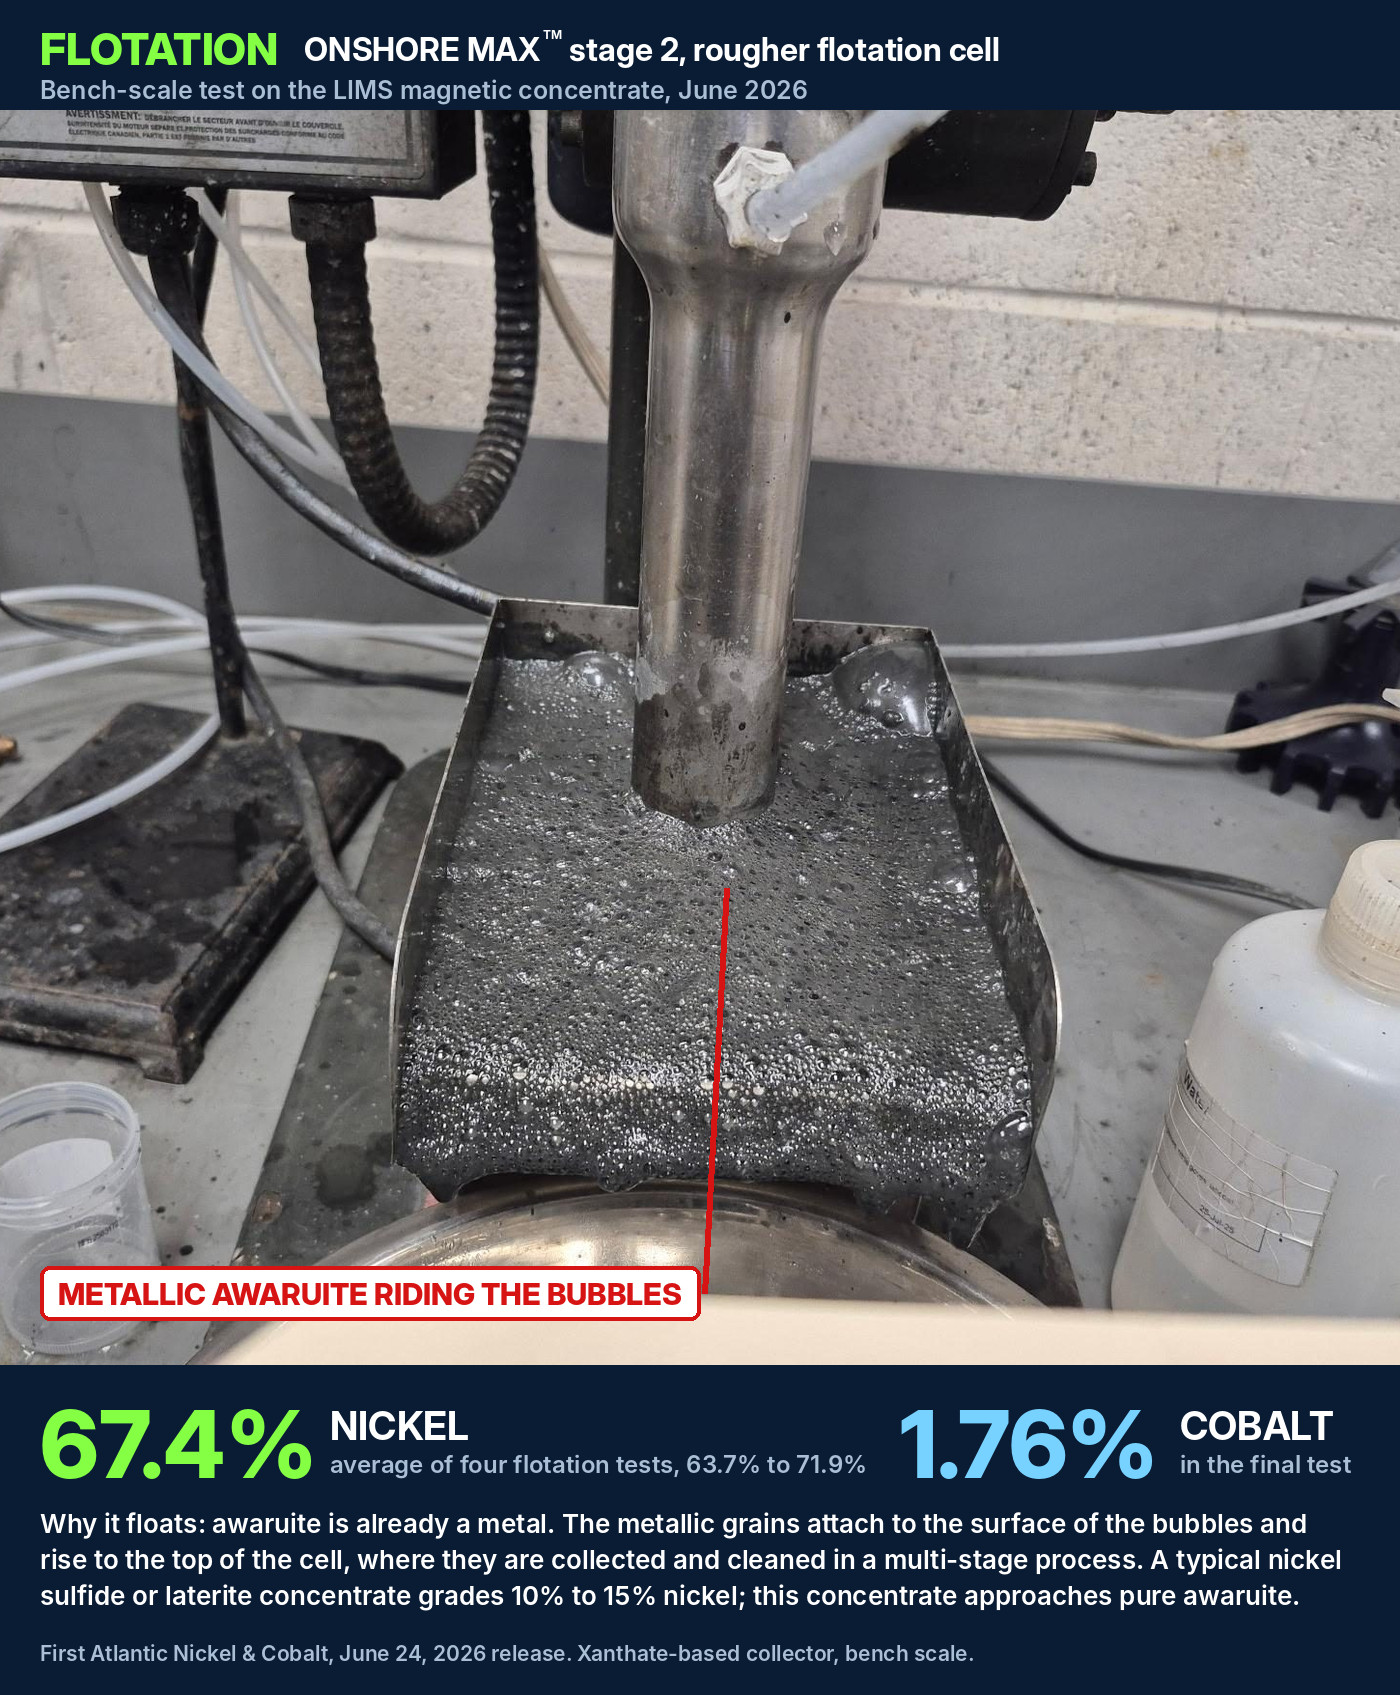
On June 24, First Atlantic released its first awaruite metallurgical results from SGS Canada under its ONSHORE MAX™ (Magnetic Alloy eXtraction) process, using RPM Zone discovery core.[13]
 1Magnetic separator drum
 2Flotation
 3Ni-CoAlloy Concentrate67.4%Nickel1.76%Cobalt
- 1Step 1Magnetic separator drumAwaruite sticks to the drum and separates from the rest of the rock.
- 2Step 2FlotationAir bubbles lift the metal grains to the top to be skimmed off.
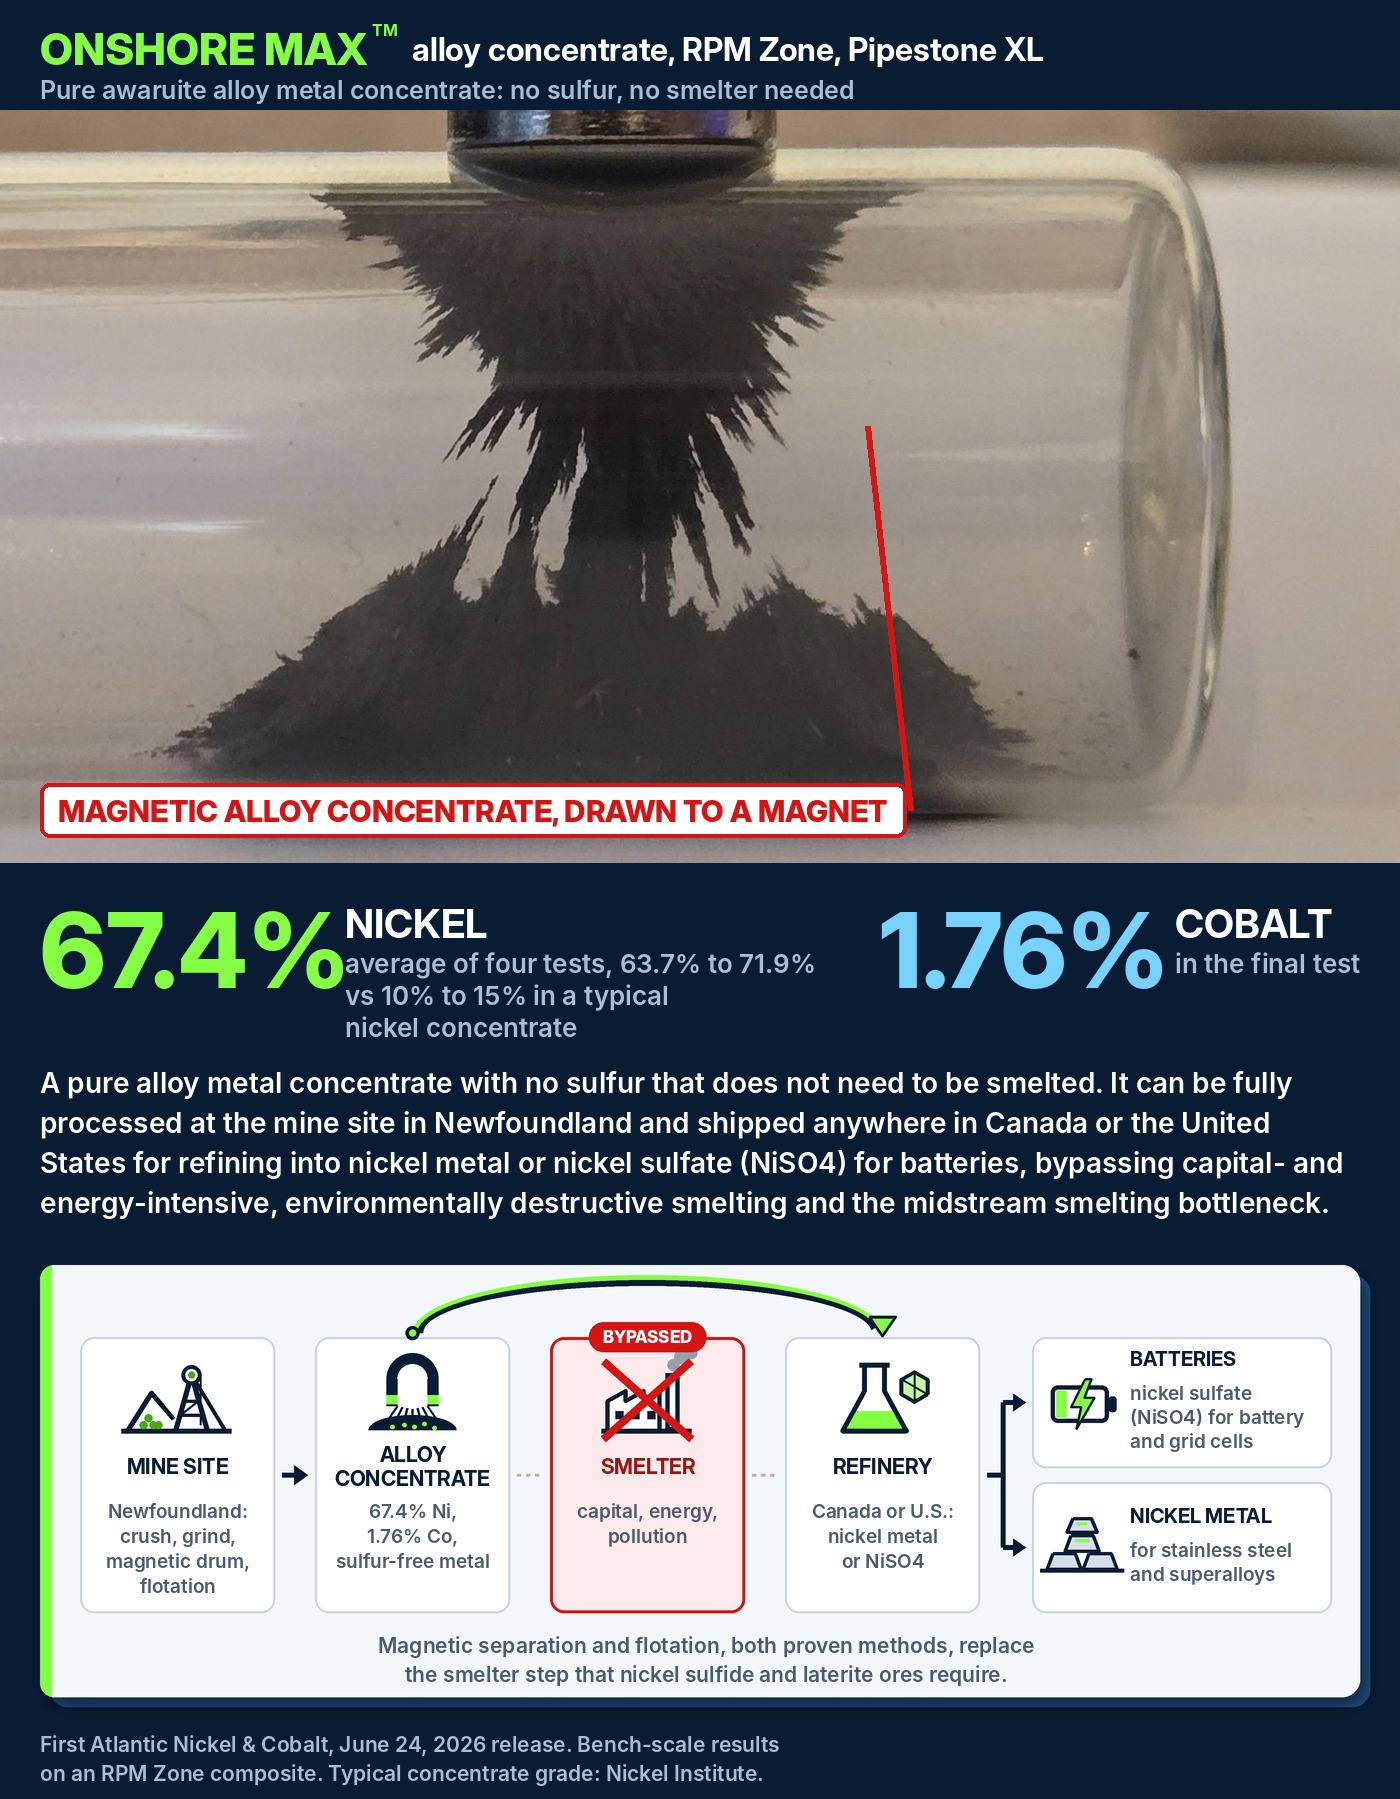
- 3Step 3Ni-Co alloy concentrateFour flotation tests averaged 67.4% nickel, from 63.7% to 71.9%, with 1.76% cobalt in the final test.[13]
- 4Step 4RefineryRefined into nickel metal or nickel sulfate for batteries.
How a Vertically Integrated Awaruite Supply Chain Could Work: Mine Site to Refinery, No Smelter
Magnetic separation and flotation, both proven methods, replace the smelter step that nickel sulfide and laterite ores require.
Nickel sulfide concentrates typically run 10% to 15% nickel, per the Nickel Institute,[13] more than four times lower than awaruite’s 67.4%, so every ton shipped carries far less metal.
| Awaruite at Pipestone XL | Sulfide and laterite nickel | |
|---|---|---|
Nickel grade | ✓About 77% nickel, a natural metal alloy | ✕About 25% nickel in sulfide; 1% to 2% in laterite |
Concentrate grade | ✓67.4% nickel average, 63.7% to 71.9%, with 1.76% cobalt | ✕Commonly 10% to 15% nickel, as low as 1% |
Mine-site processing | ✓Magnetic separation and flotation | ✕Flotation, smelting, roasting or high-pressure acid leaching |
Secondary processing | ✓Not required, concentrate ships direct to a refinery | ✕Required: potentially billions in capex for a smelter or HPAL (high-pressure acid leach) plant, plus the energy to run it |
Smelter charges (TC/RC) | ✓None, it does not need to be smelted at all | ✕Charged per tonne of concentrate and deducted from the miner’s payment, plus shipping, and when the smelter is in another country, potential export and import taxes and tariffs on top |
Electricity demand | ✓Low | ✕Higher |
Pollution from acid-generating mine waste | ✓None | ✕Toxic SO2, acid mine drainage, sulfuric acid waste |
Tailings | ✓Sulfur-free and inert | ✕Toxic and acid-generating |
Permitting | ✓Faster | ✕Harder: acid mine drainage and water issues |
The difference is in the mineral. Awaruite is already an alloy, so the smelter, its charges, its power and its acid waste drop out of the chain.[12] That is ONSHORE MAX™.
Pipestone XL Geology and Drilling: The RPM Zone, Then the Alloy Max North and Alloy Max South Awaruite Discoveries in 2026
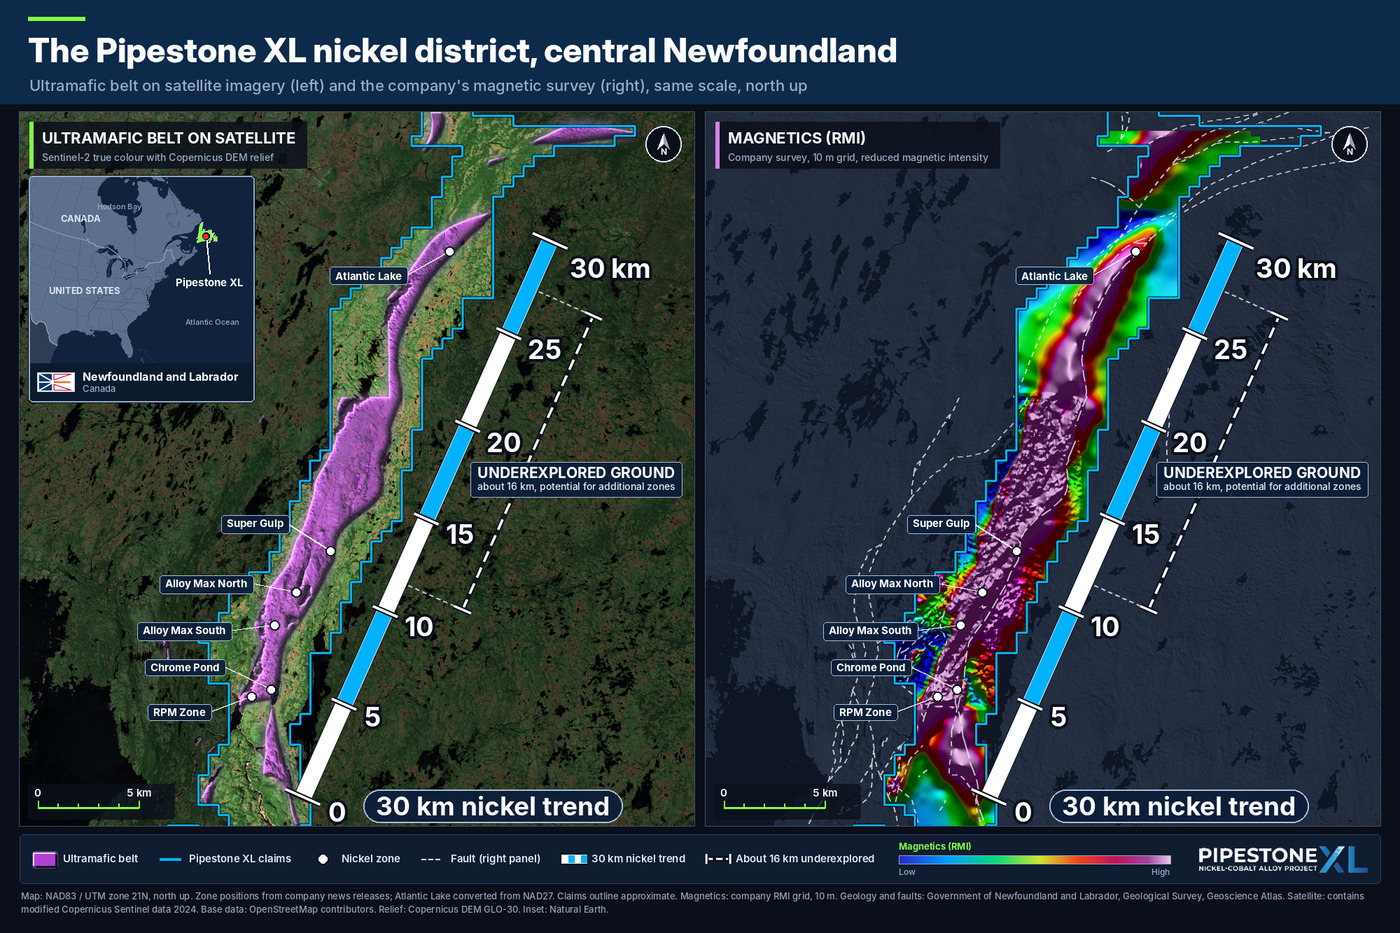
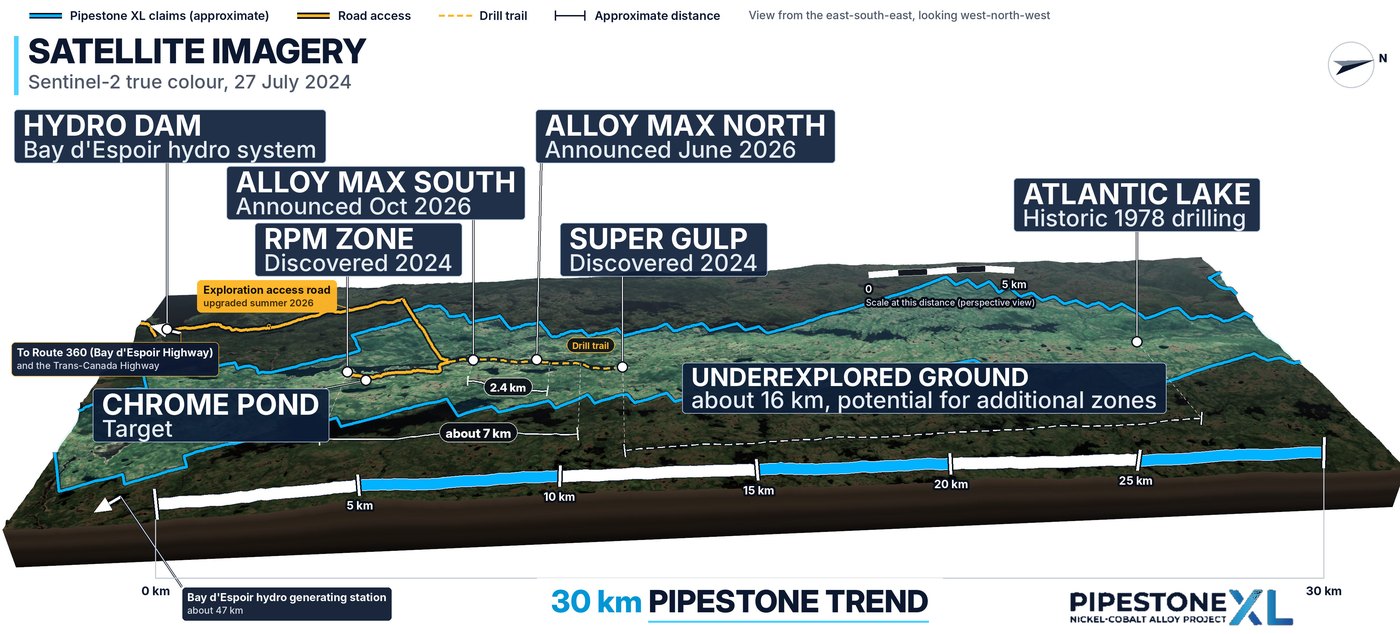
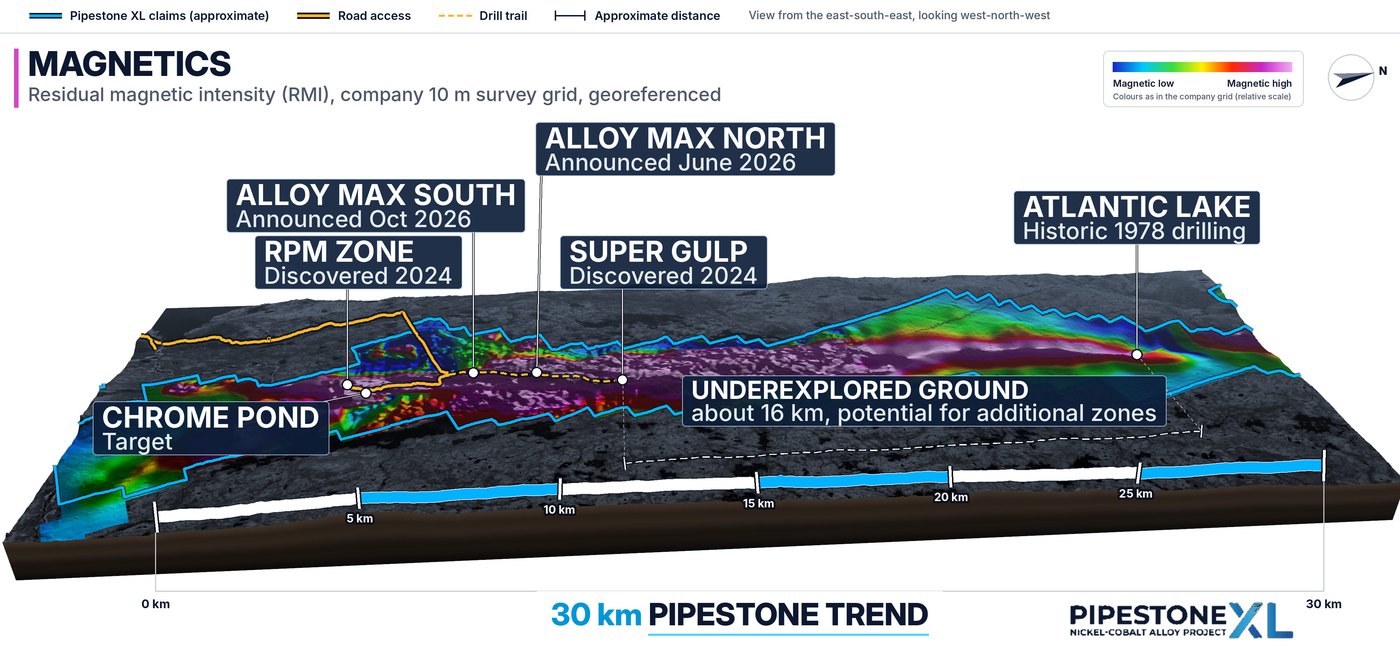
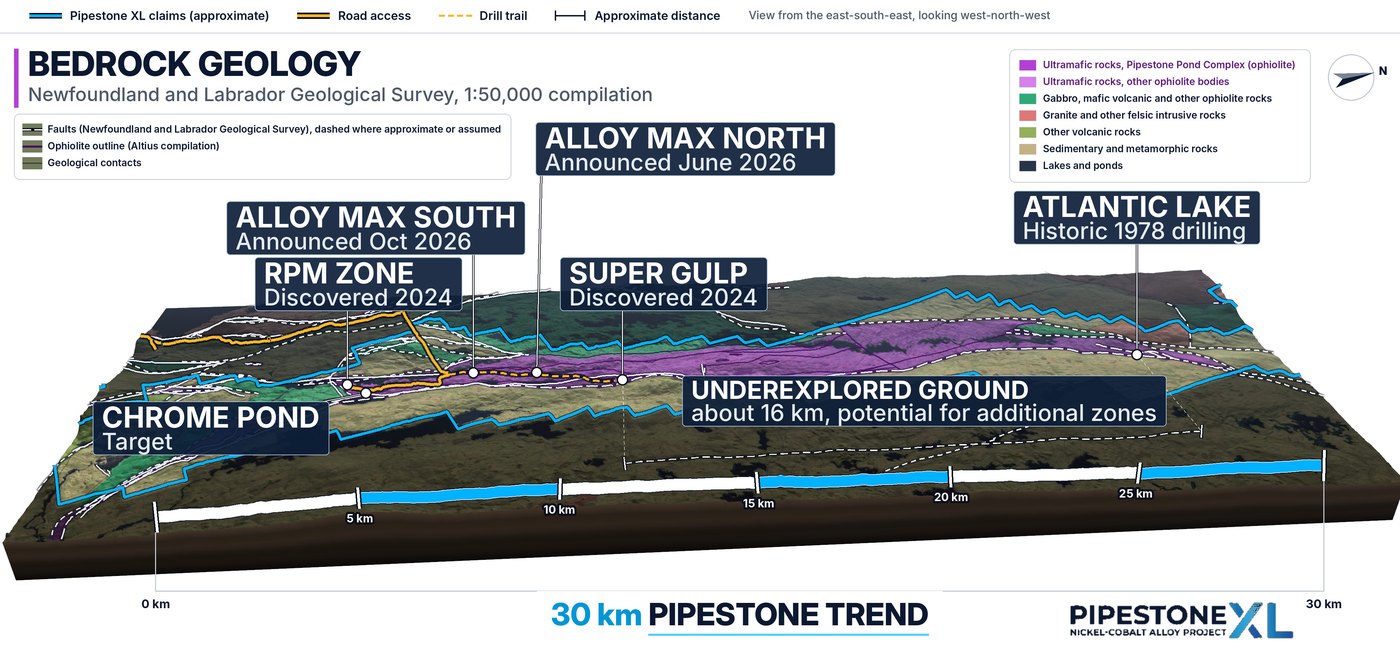
Pipestone XL covers the 30 km Pipestone Ophiolite Complex, ancient ocean crust and mantle thrust onto land along the Appalachian Orogen and enriched in nickel, cobalt and chromium by serpentinization.
Click the map for a larger, high-resolution view
+ More about this figure− Less
Click the map for a larger, high-resolution view
+ More about this figure− Less
Click the map for a larger, high-resolution view
+ More about this figure− Less
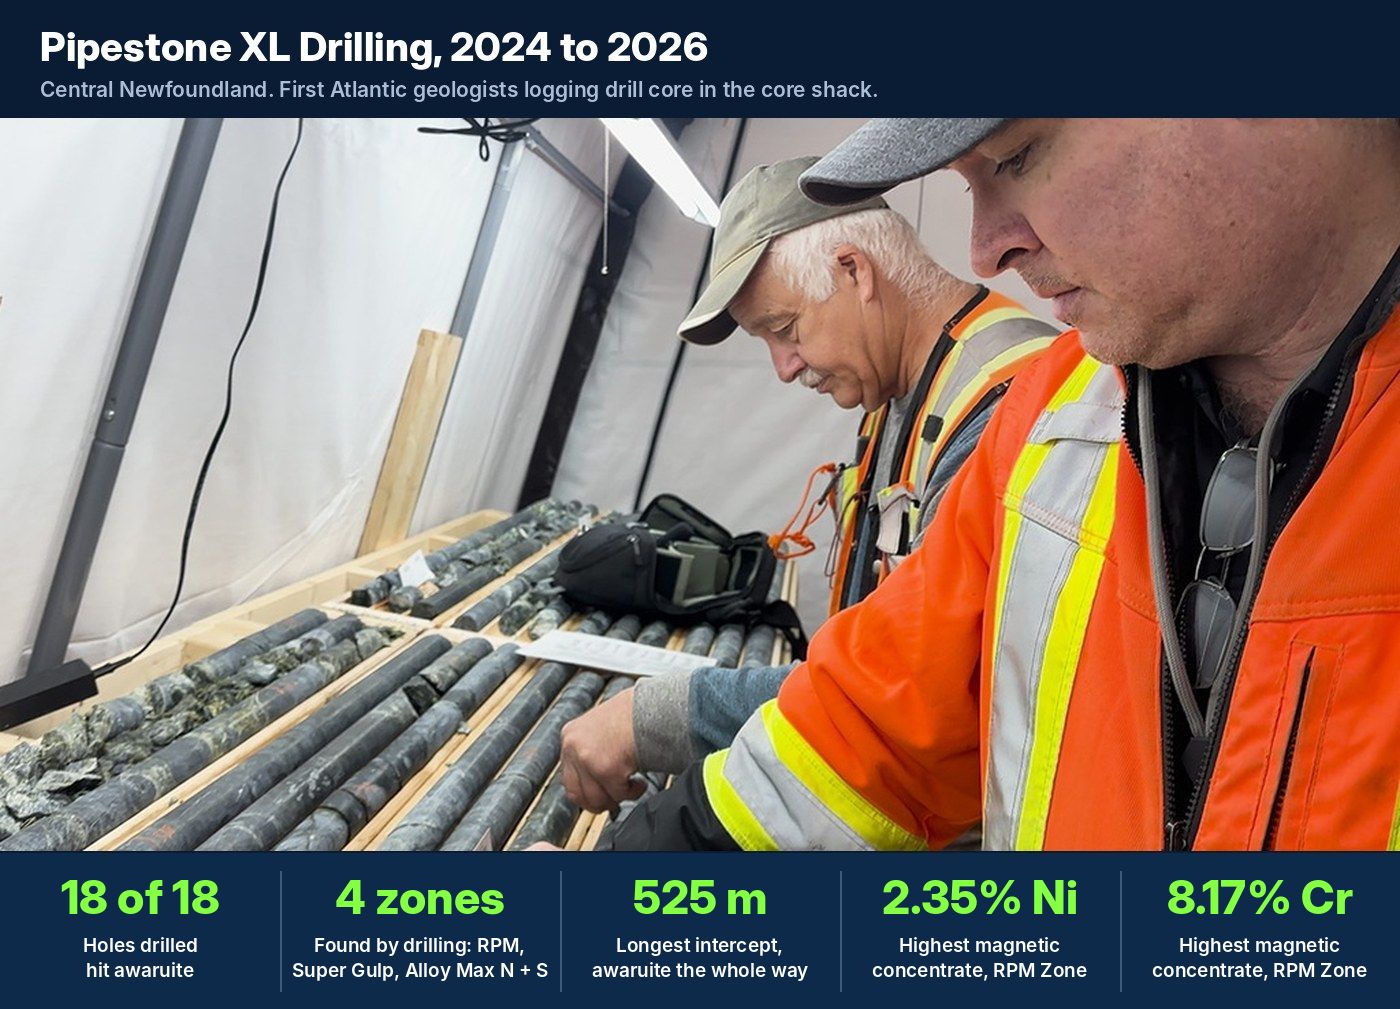
Every drill hole has hit. All 18 holes since 2024 intersected awaruite with chromite, from AN-24-01 at Super Gulp, mineralized from surface over its full 297 metres, to 13 at RPM and 4 at Alloy Max.[73][16][14]
+ More about this figure− Less
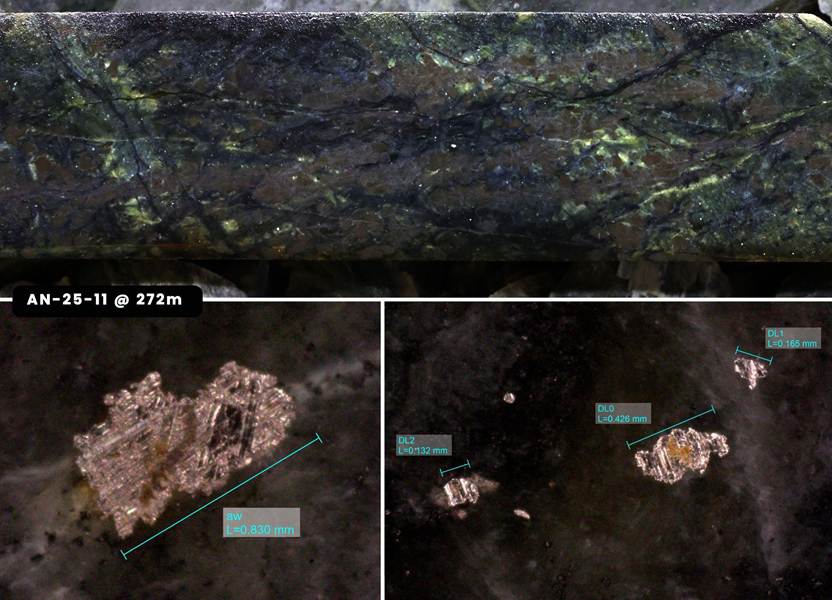
RPM Zone, 2024 and 2025. Thirteen holes, all positive, expanded RPM to more than 1.2 km of strike and 800 meters of width,[16] with intercepts up to 447 meters and magnetic concentrates up to 2.35% nickel (AN-25-06) and 8.17% chromium (AN-24-02).[75][76]
+ More about this figure− Less
Wide, consistent, disseminated mineralization of this kind is ideal for a large-scale open-pit mine. RPM drill results in order: DTR nickel, what a magnet pulls from the rock, and the concentrate grade of that fraction.[16]
Show all 13 holesHide the table
| Hole | Sec. | From | To | Length (m) | DTR Ni % | Conc. Ni % | Reported |
|---|---|---|---|---|---|---|---|
| AN-24-02 | S1 | 11 | 394 | 383 | 0.13 | 1.37 | Mar 12, 2025 |
| AN-24-03 | S1 | 18 | 234 | 216 | 0.11 | 1.32 | Apr 15, 2025 |
| AN-24-04 | S1 | 12 | 378 | 366 | 0.14 | 1.46 | Jun 24, 2025 |
| AN-24-05 | S2 | 6 | 357 | 351 | 0.12 | 1.47 | Jul 9, 2025 |
| AN-25-06 | S2 | 5.65 | 453 | 447 | 0.11 | 1.27 | Aug 12, 2025 |
| AN-25-07 | S2 | 9 | 495 | 486 | 0.09 | 0.97 | Oct 23, 2025 |
| AN-25-08 | S3 | 11 | 491 | 480 | 0.12 | 1.35 | Oct 23, 2025 |
| AN-25-09 | S3 | 9 | 483 | 474 | 0.08 | 0.93 | Dec 2, 2025 |
| AN-25-10 | S1 | 8 | 236 | 228 | 0.15 | 1.44 | Dec 2, 2025 |
| AN-25-11 | S1 | 23 | 425 | 402 | 0.13 | 1.31 | Jan 27, 2026 |
| AN-25-12 | S1 | 10.4 | 95 | 84.6 | 0.10 | 1.24 | Jan 27, 2026 |
| AN-25-13 | S4 | 17 | 388 | 371 | 0.10 | 1.11 | Jan 27, 2026 |
| AN-25-14 | S0 | 8 | 335 | 327 | 0.05 | 0.54 | Jan 27, 2026 |
Source: company news releases, March 12, 2025 to January 27, 2026, as tabulated in the January 27, 2026 release. Intervals are drilled lengths, not true widths.
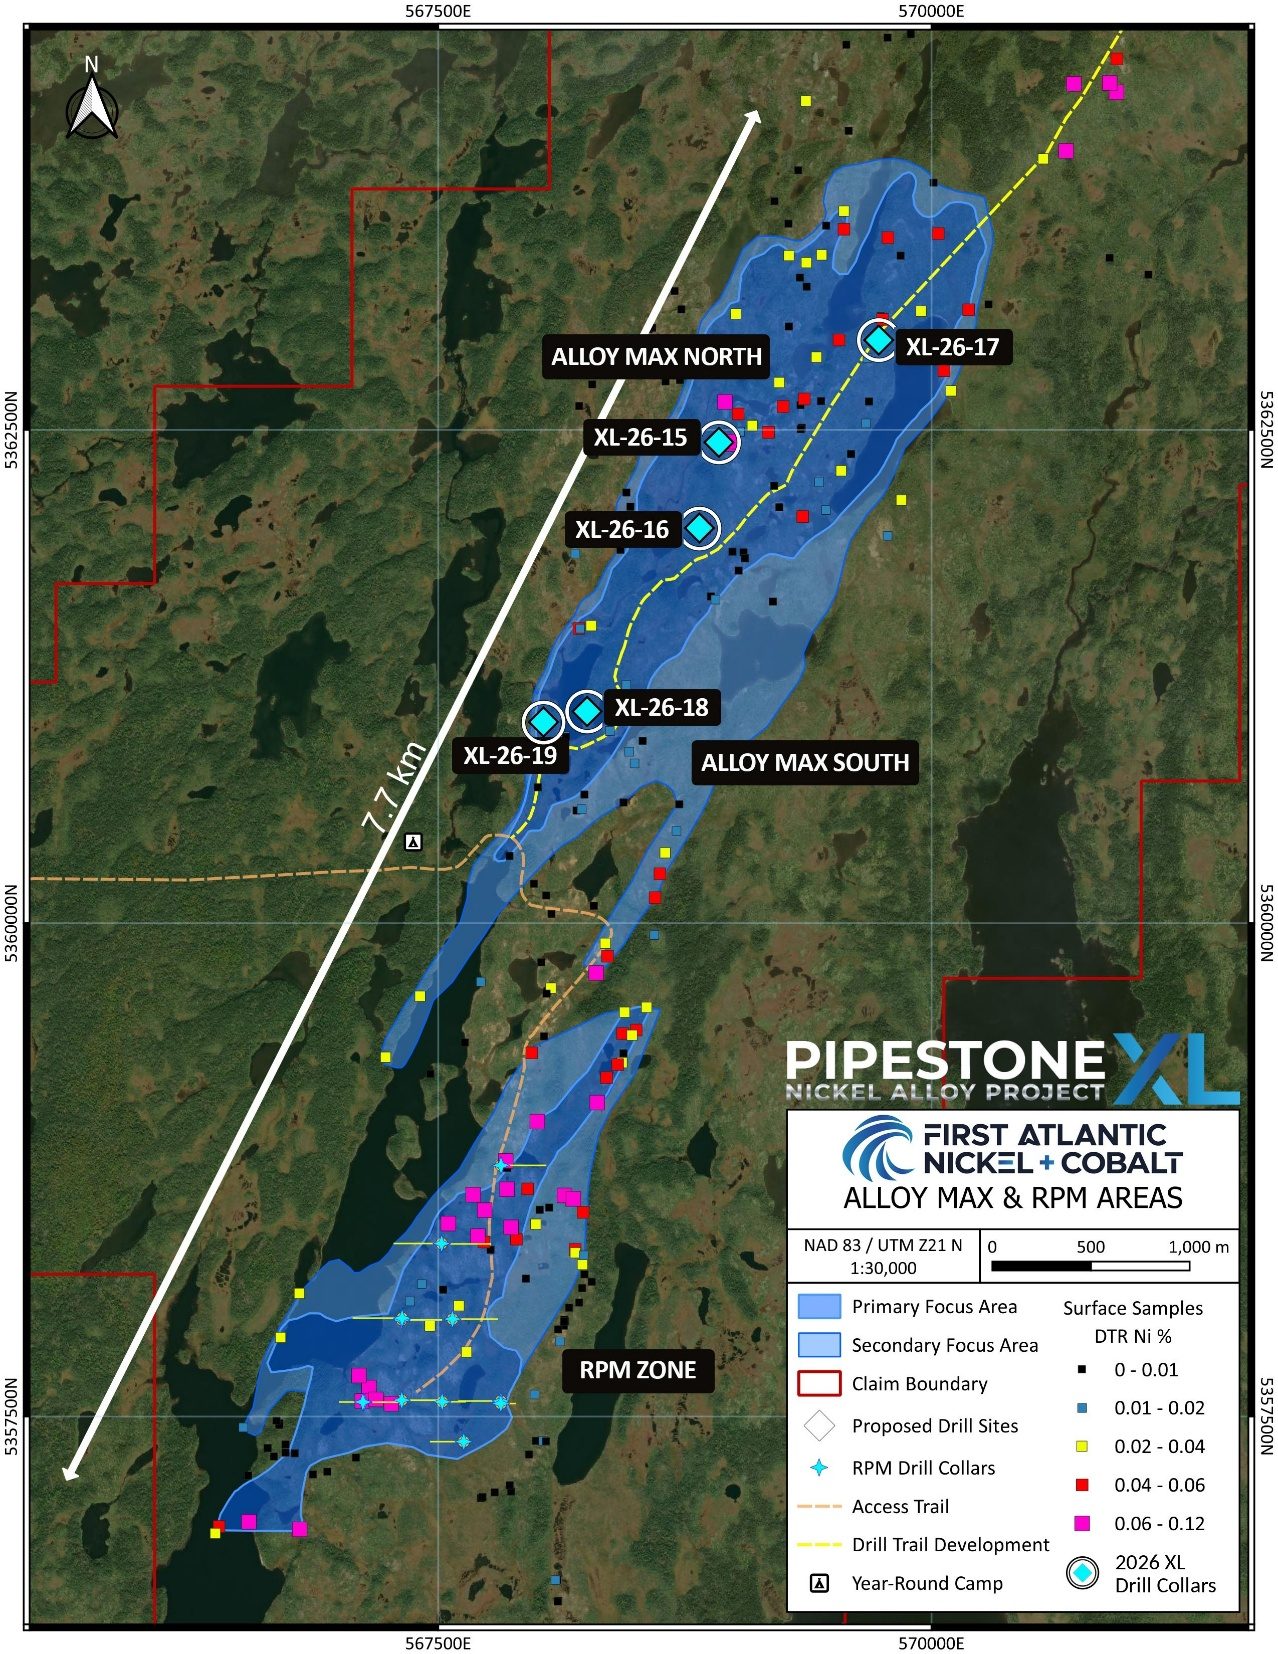
Alloy Max, 2026. Announced March 18, Alloy Max lies about 7 km north of RPM and is mapped at about 4 km long.[77] Drilling has found awaruite in two areas 2.4 km apart:
- XL-26-15, June 15, Alloy Max North: the discovery hole hit visible awaruite over its entire 414 meters and ended in mineralization.[78]
- XL-26-16, July 16, Alloy Max North: about 445 meters south, the deepest hole at Pipestone XL, large-grain awaruite over its entire 525 meters.[74]
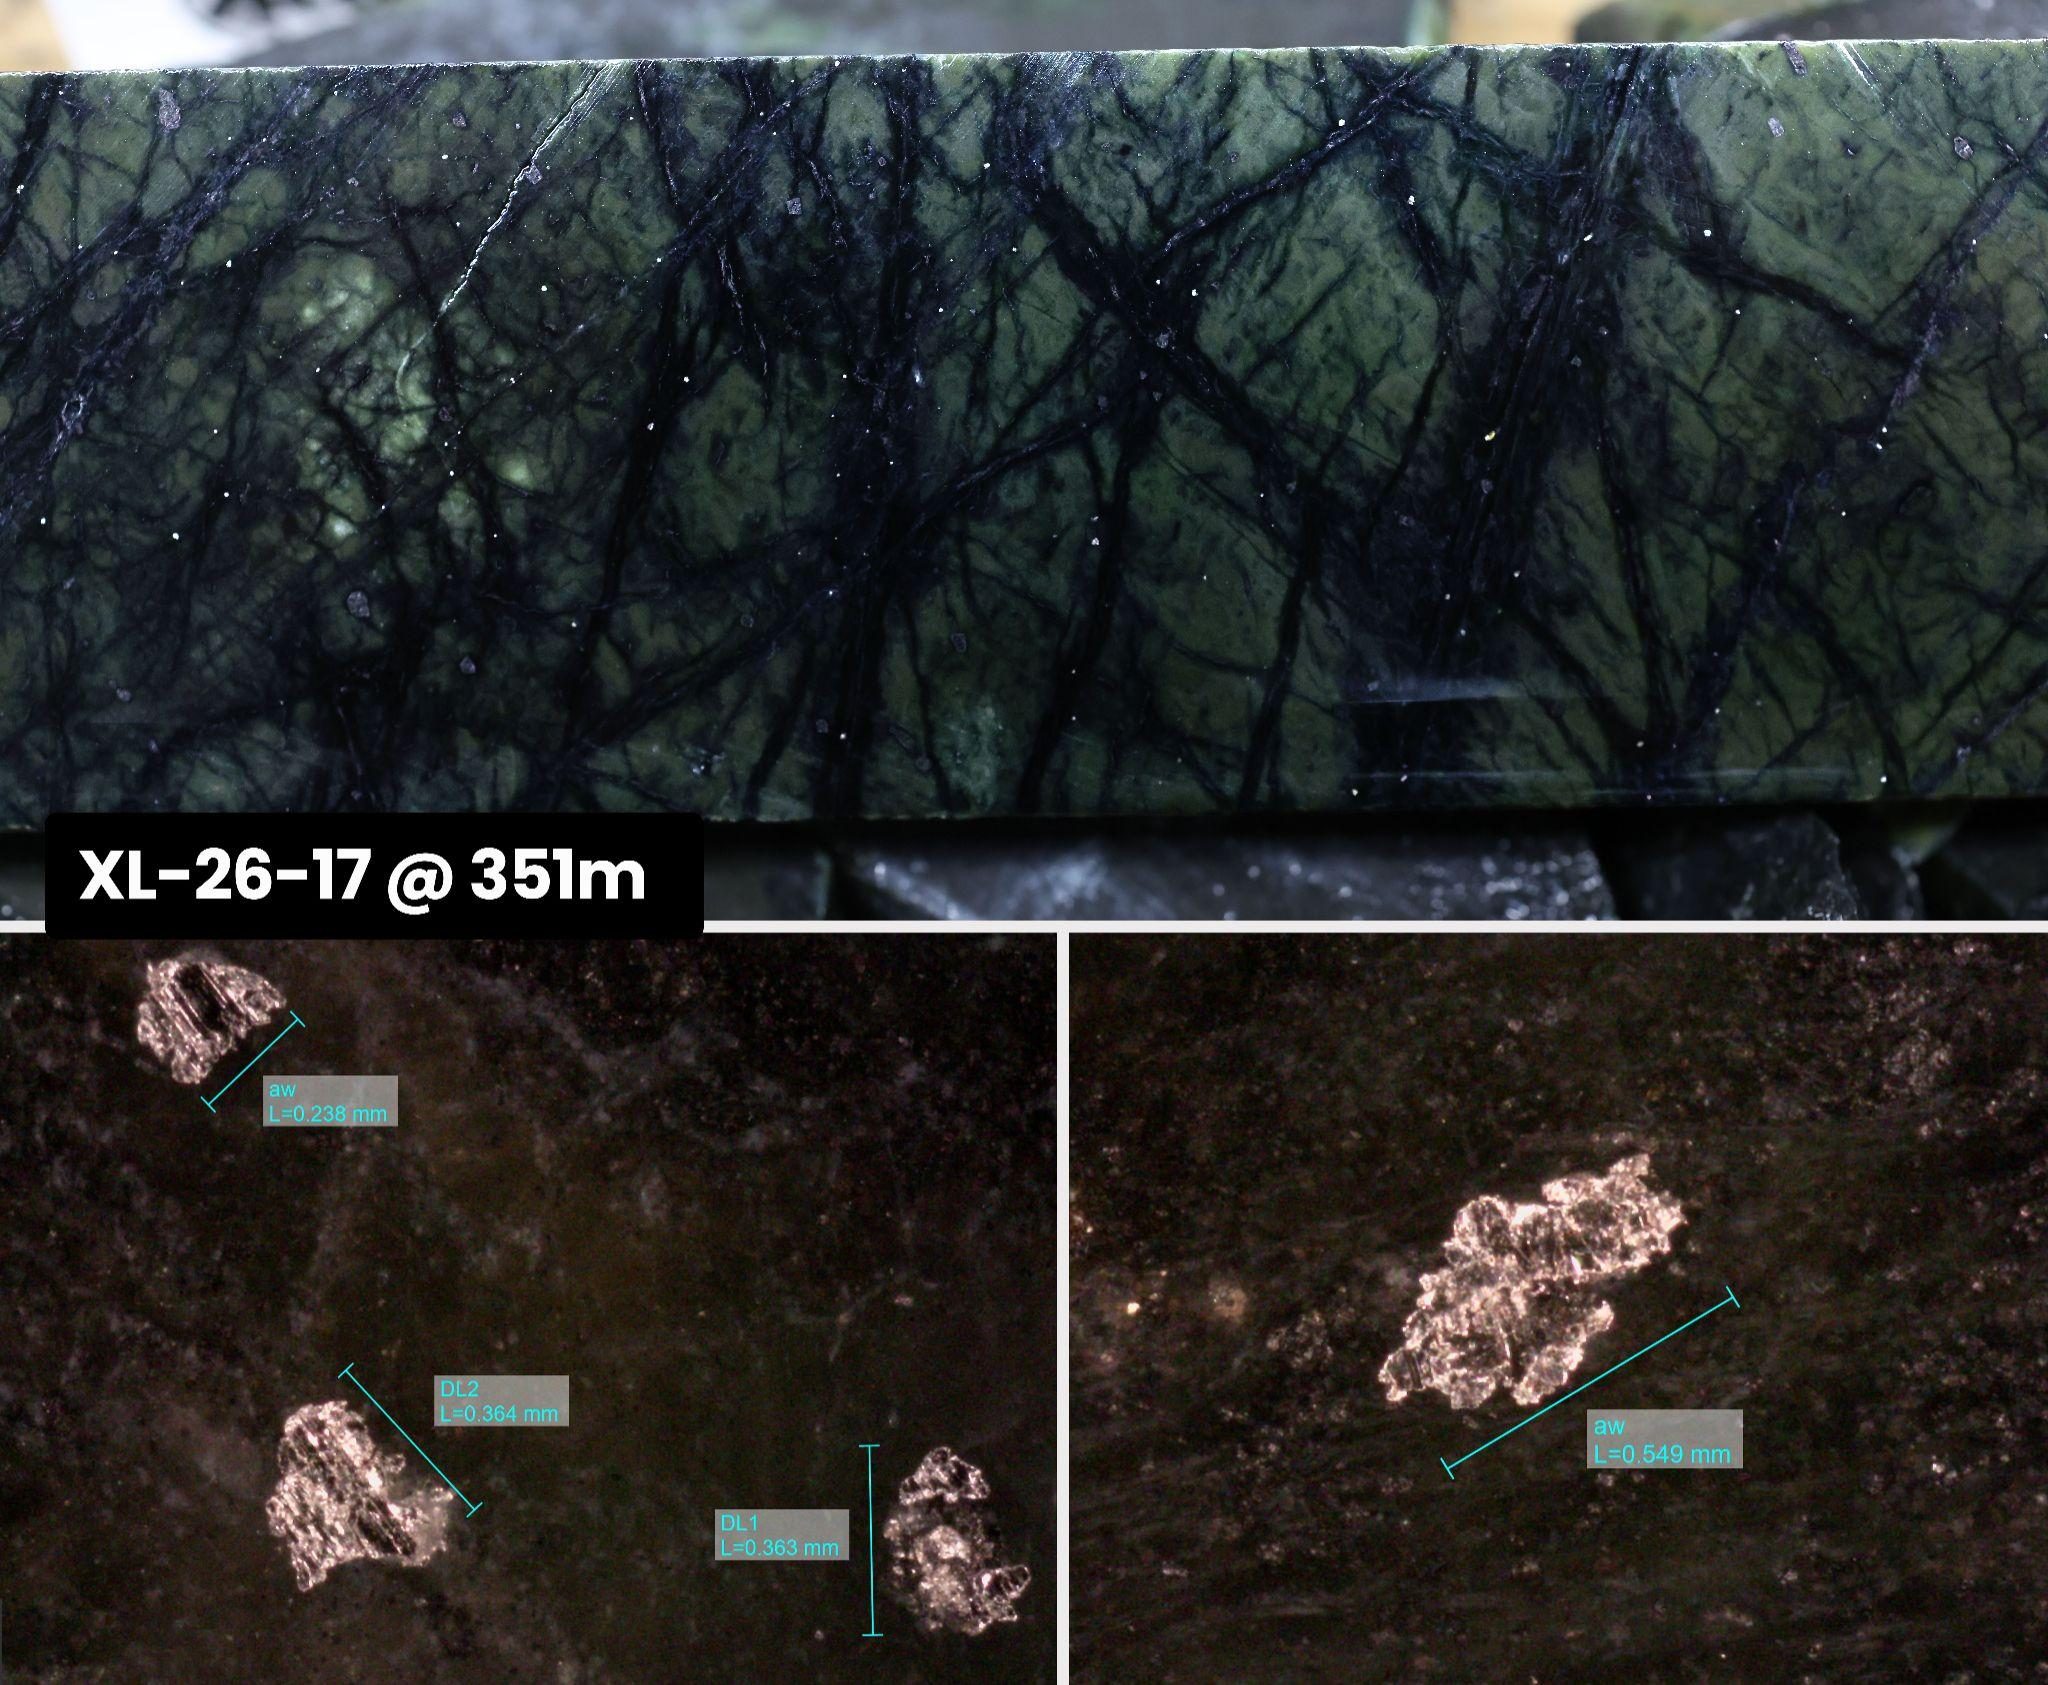
- XL-26-17, October 13, Alloy Max North: the northernmost hole, with grains up to 549 microns at 351 meters, the largest at Alloy Max.[14]
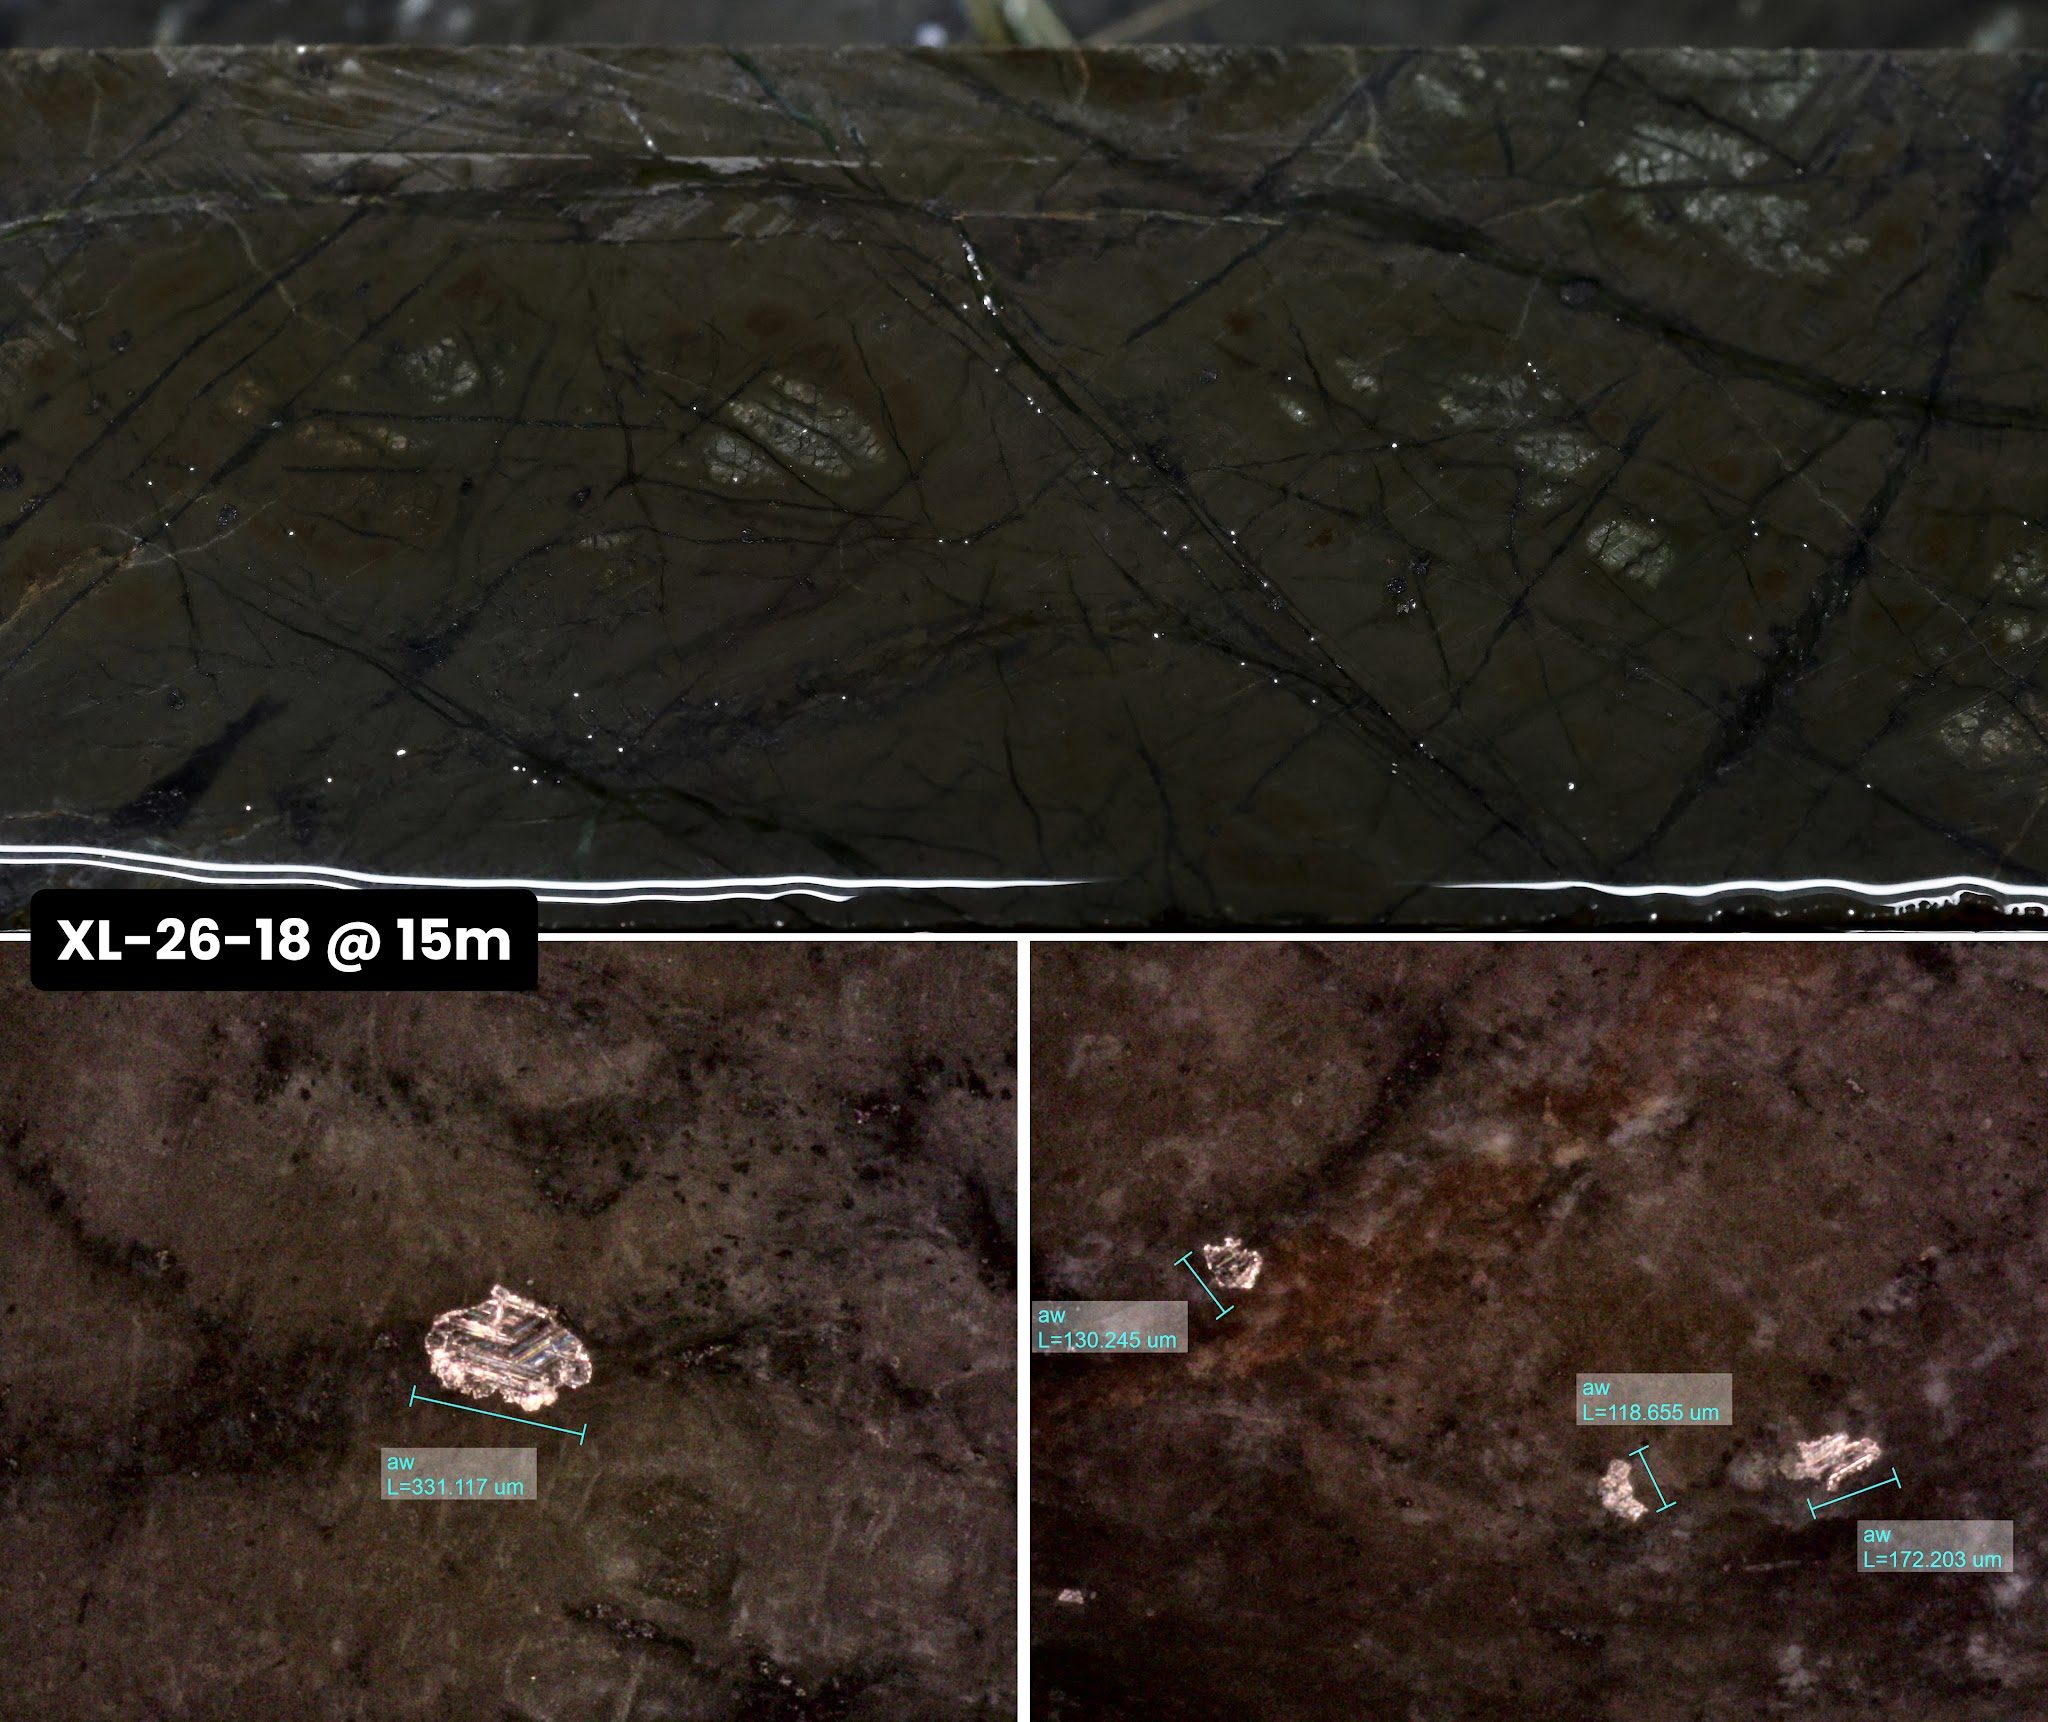
- XL-26-18, October 13, Alloy Max South: discovery hole of the Alloy Max South Zone, 2.4 km southwest, with large-grain awaruite from 15 meters down.[14]
+ More about this figure− Less
Click the map for a larger, high-resolution view
+ More about this figure− Less
Alloy Max now spans about 2.4 km of strike and over 1 km of width.[14] XL-26-18 ended in awaruite at about 40 meters in faulted ground; follow-up XL-26-19 is testing below it.[14]
+ More about this figure− Less
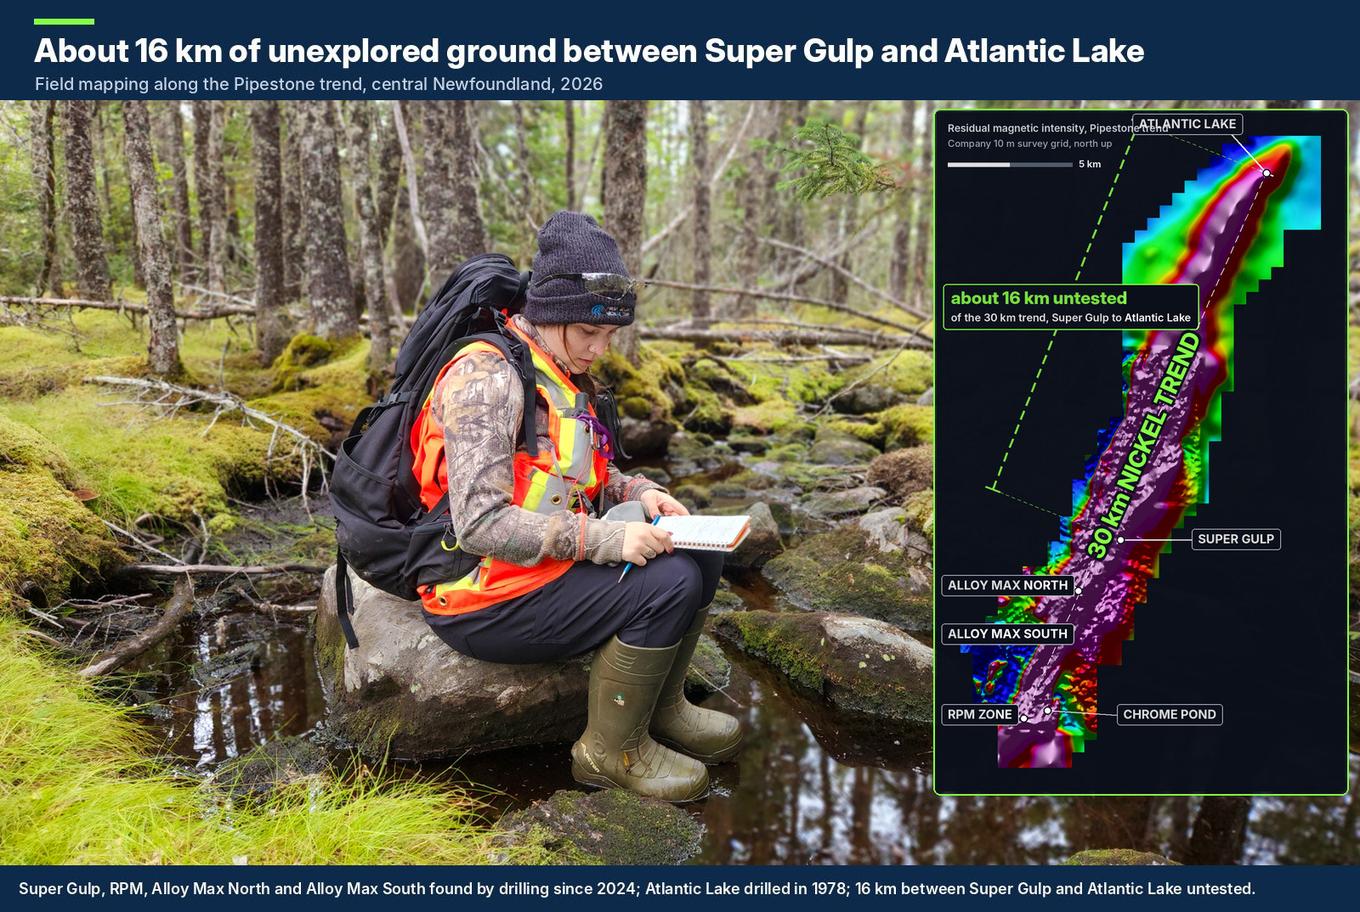
Five zones, potential for multiple pits. Beyond RPM and Alloy Max lie Super Gulp, the historic Atlantic Lake zone and the Chrome Pond target,[14] and about 16 km, roughly half the belt, is still underexplored. Each shallow zone is a candidate open-pit, bulk-tonnage feed for one central ONSHORE MAX™ concentrator,[77] and with minimal overburden and road access, each that drills like RPM adds a potential pit.[77]
Click the map for a larger, high-resolution view
+ More about this figure− Less
Hydrogen and Chromium: The VEMA Hydrogen Joint Venture and Chromium at Pipestone XL
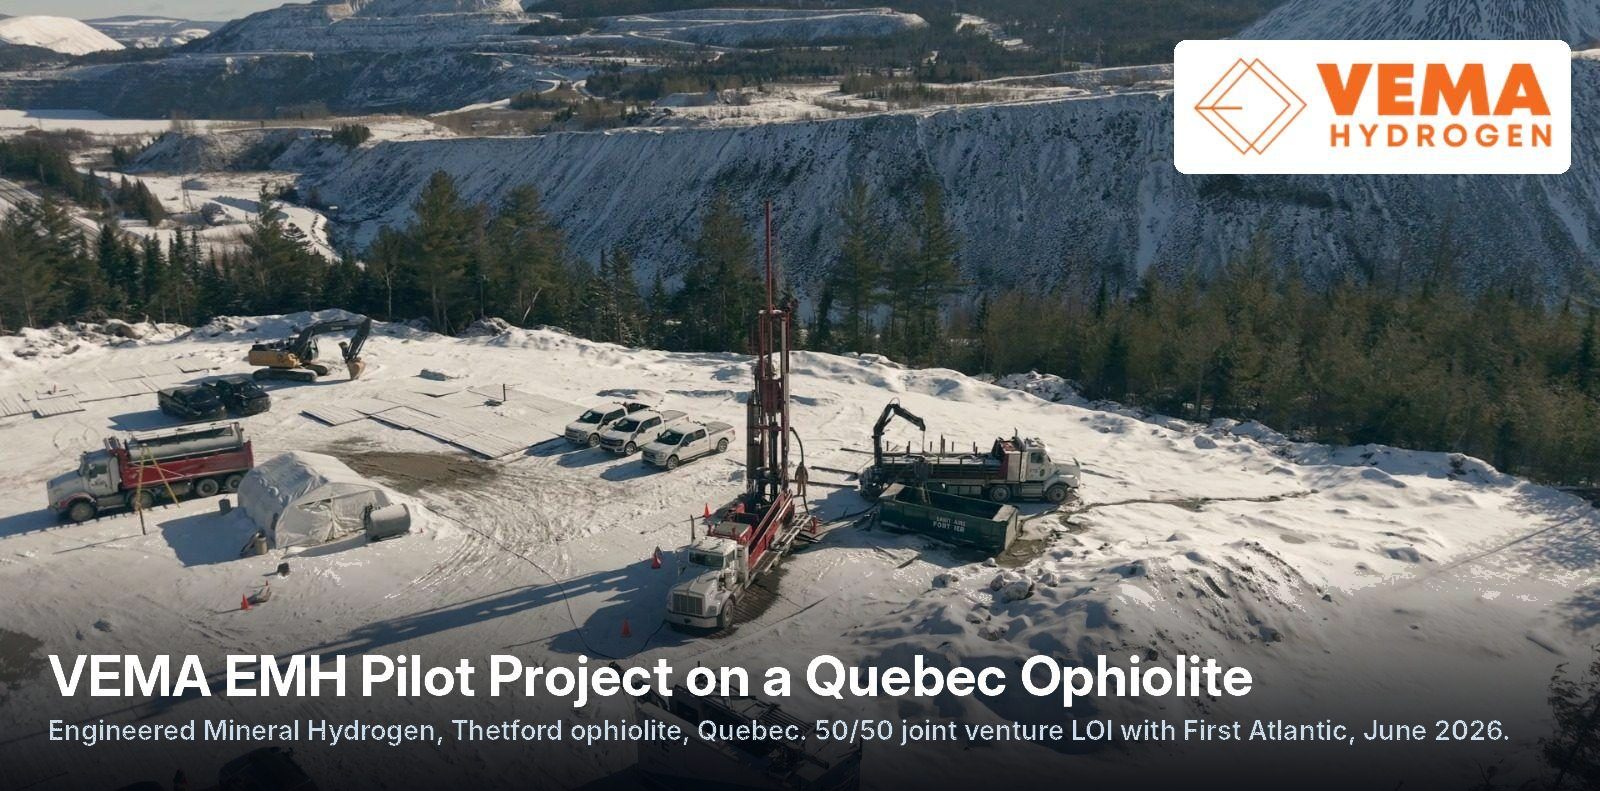
At First Atlantic’s Ophiolite-X project, natural springs discharge hydrogen from active serpentinization, and a study cited by the company puts production costs below the U.S. Department of Energy’s $1/kg target.[79]
On June 8, 2026, Vema Hydrogen and First Atlantic signed a non-binding letter of intent for a 50/50 joint venture in Engineered Mineral Hydrogen (EMH) at Pipestone XL, where Vema’s lab tests confirmed hydrogen production.[80]
+ More about this figure− Less
Strategic Advisor, First Atlantic Nickel & Cobalt
Former Program Director, ARPA-E, U.S. Department of Energy
 FormerARPA-E, U.S. Department of Energy
“Vema’s Engineered Mineral Hydrogen is on the verge of delivering clean energy at a scale cost-competitive with hydrocarbons. Awaruite forms through serpentinization when hydrogen reduces nickel and iron, so its presence at Pipestone XL is a clear signature of a hydrogen-rich system. Vema’s technology could engineer that same reaction for hydrogen production, and Pipestone XL is an ideal location due to its size, proximity to infrastructure, and the potential for cost efficiencies in co-locating hydrogen production with nickel & cobalt mining. Having worked closely with Vema’s founders since before the company’s founding, and having seen firsthand how they developed the engineered approach to geologic hydrogen, I believe Pipestone XL represents a compelling opportunity to bring this technology to commercial scale.”[80]
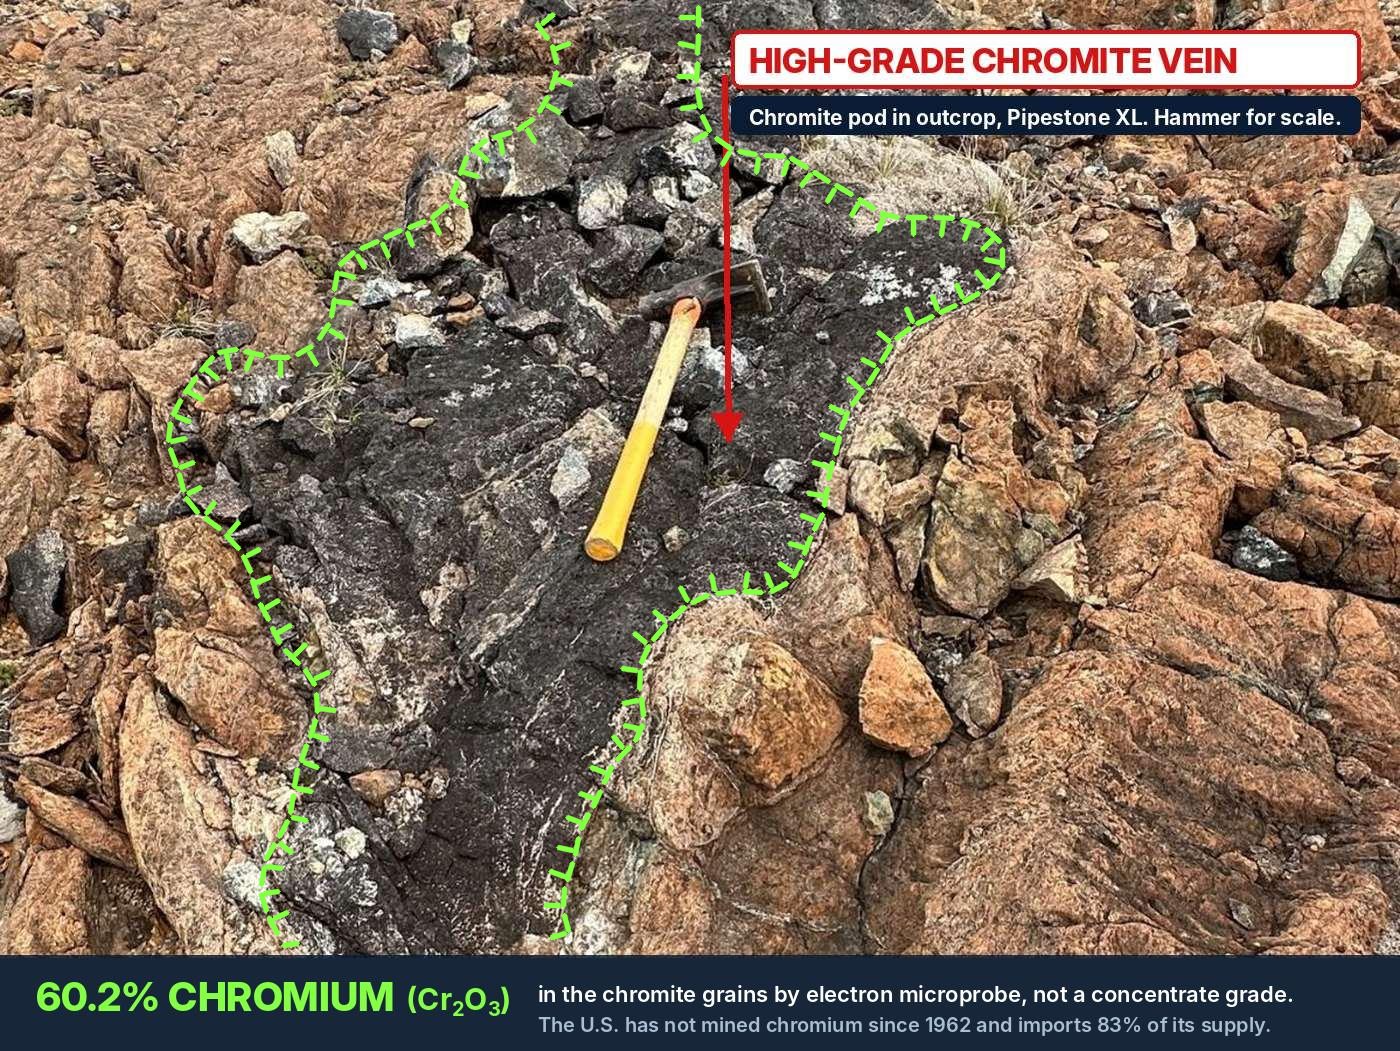
Chromium. Microprobe analysis confirmed chromite grading 60.2% Cr2O3, now being tested as a co-product.[12] Canada’s largest chromite prospect, the Ring of Fire’s Black Thor, grades below the benchmark for ferrochrome and stainless steel ore.[81][82] North America mines no chromium, and there is no substitute for chromium in stainless steel.[83]
+ More about this figure− Less
Nickel and Cobalt Demand and China’s Control of Supply: IMF, IEA, Carnegie Endowment and Indonesia
The International Monetary Fund values nickel production from 2021 to 2040 at $4.1 trillion and cobalt at $1.6 trillion;[84] the International Energy Agency sees 60 new nickel mines and 17 new cobalt mines needed by 2030.[85]
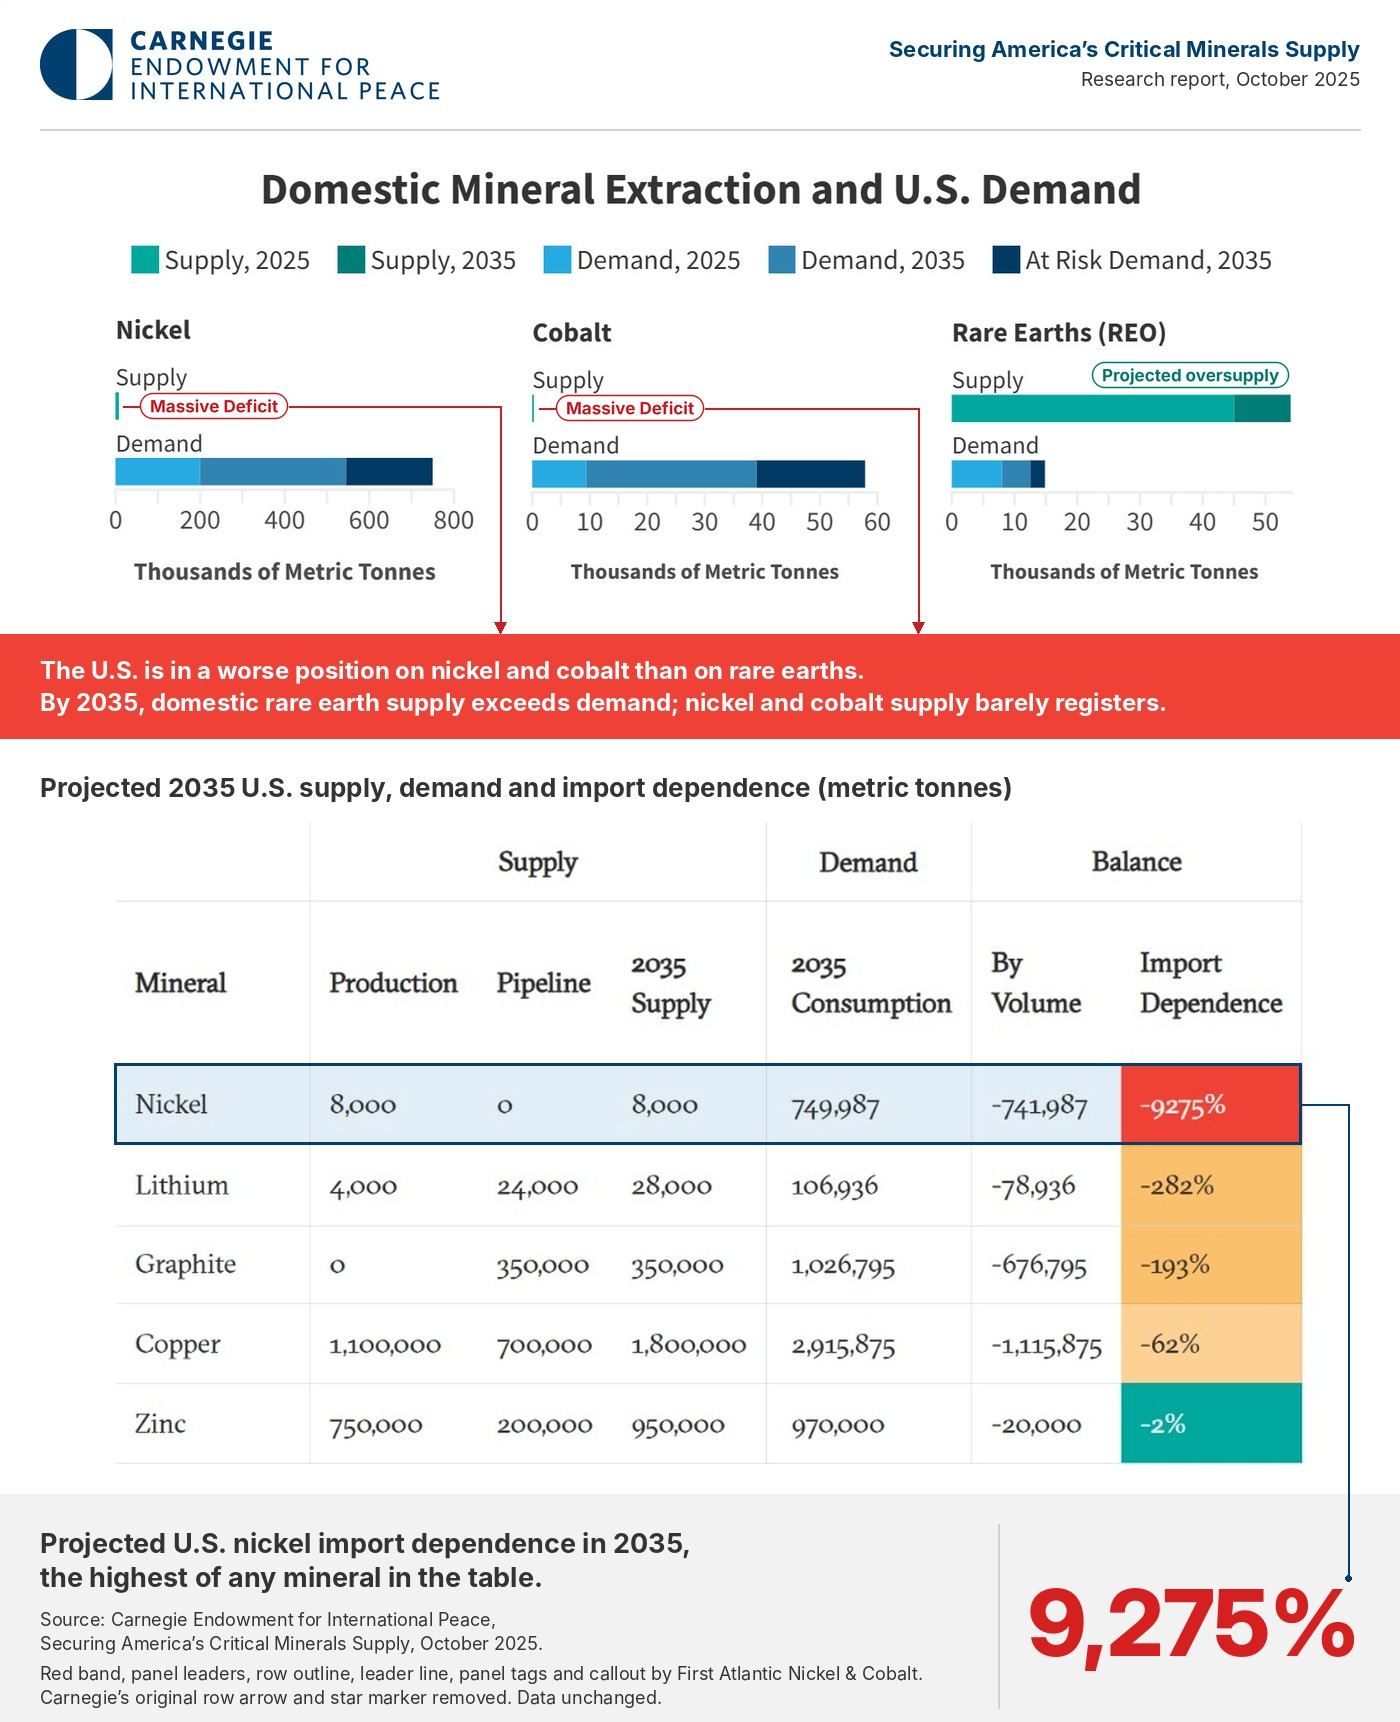
The United States holds less than 1% of global nickel reserves.[86] By 2035 its nickel import reliance is projected at 9,275%, the highest of any critical mineral, according to the Carnegie Endowment for International Peace. That leaves the United States in a worse position on nickel and cobalt than on the rare earths that get the headlines: Carnegie’s own chart shows domestic supply of those elements above demand by 2035, while nickel and cobalt supply barely registers against demand, and Canada is the supplier it already leans on for 44% of its primary nickel imports.[87][22]
+ More about this figure− Less
Supply is concentrated where China invests. Indonesia mines more than 60% of the world’s nickel; after its 2020 ore export ban, Chinese state-backed companies invested an estimated $65 billion, and Indonesia’s parliament says China controls 90% of its nickel industry.[88]
First Atlantic Nickel & Cobalt (OTCQB: FANCF, TSX-V: FAN), processed without a smelter, sits outside that system.
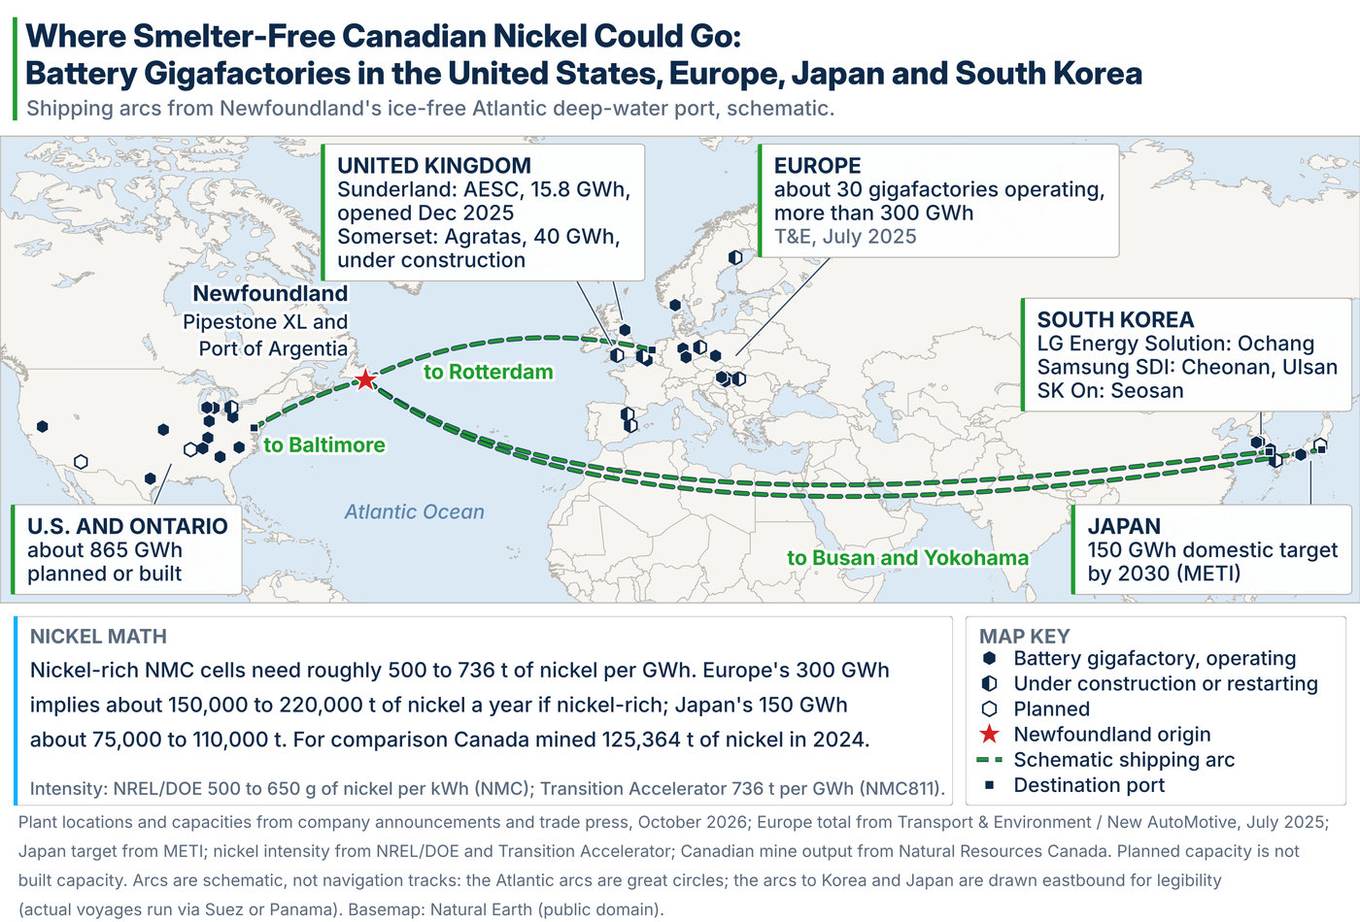
Where Smelter-Free Canadian Nickel Would Go: Europe, Japan, Korea and the United States, and the Gigafactories Behind the Demand
Canada is a small nickel consumer, so the market is abroad. Europe, Japan and the United States each use hundreds of thousands of tonnes of nickel a year.[89] Europe still gets 15% of its nickel imports from Russia, unsanctioned by the European Union,[90] and its Critical Raw Materials Act sets a 65% ceiling on any one outside supplier by 2030, with battery-grade nickel on its strategic list.[91][92]
Newfoundland and Labrador already produces 14% of Canada’s nickel and 28% of its cobalt from Voisey’s Bay and refines nickel at Long Harbour.[1][93]
The biggest customer next door admits it cannot process nickel or cobalt either. On January 14, 2026, in Proclamation 11001, the White House found that the United States lacks the capacity to process them:[94]
“Even where the United States has domestic mining capacity, such as for cobalt, nickel, and rare earth elements, the United States lacks the domestic processing capacity to avoid downstream net-import reliance.”[94]
The G7 has already singled nickel out. In June 2026 its leaders named nickel, with lithium, a first pilot mineral for allied critical minerals traceability,[30] and Italy was promised preferential access to Canadian reserves.[95]
Ottawa has drawn its own policy line. The Commons defence committee’s first recommendation, in October 2026, is to keep prioritizing domestic processing, refining and midstream capacity,[96] which Scotiabank calls “a vital national security and trade leverage imperative.”[97]
Canada has already signed the partners up. France, Germany, Italy and Korea intend to stockpile critical minerals with Canada,[98] and the Canada-UK statement calls Canadian nickel and cobalt “some of the least emissions intensive in the world.”[99] Samsung SDI holds an option on 10% of Canada Nickel’s Crawford nickel and cobalt,[100] and Sumitomo Metal Mining took 9.9% of FPX Nickel, an awaruite developer in British Columbia.[101]
+ More about this figure− Less
The port is the other half of the story. The ice-free, deep-water Port of Argentia[103] runs straight to Rotterdam, the U.S. east coast and Asia; Carnegie projects U.S. nickel demand at about 750,000 tonnes by 2035 against 8,000 tonnes of domestic supply.[87]
Click the map for a larger, high-resolution view
+ More about this figure− Less
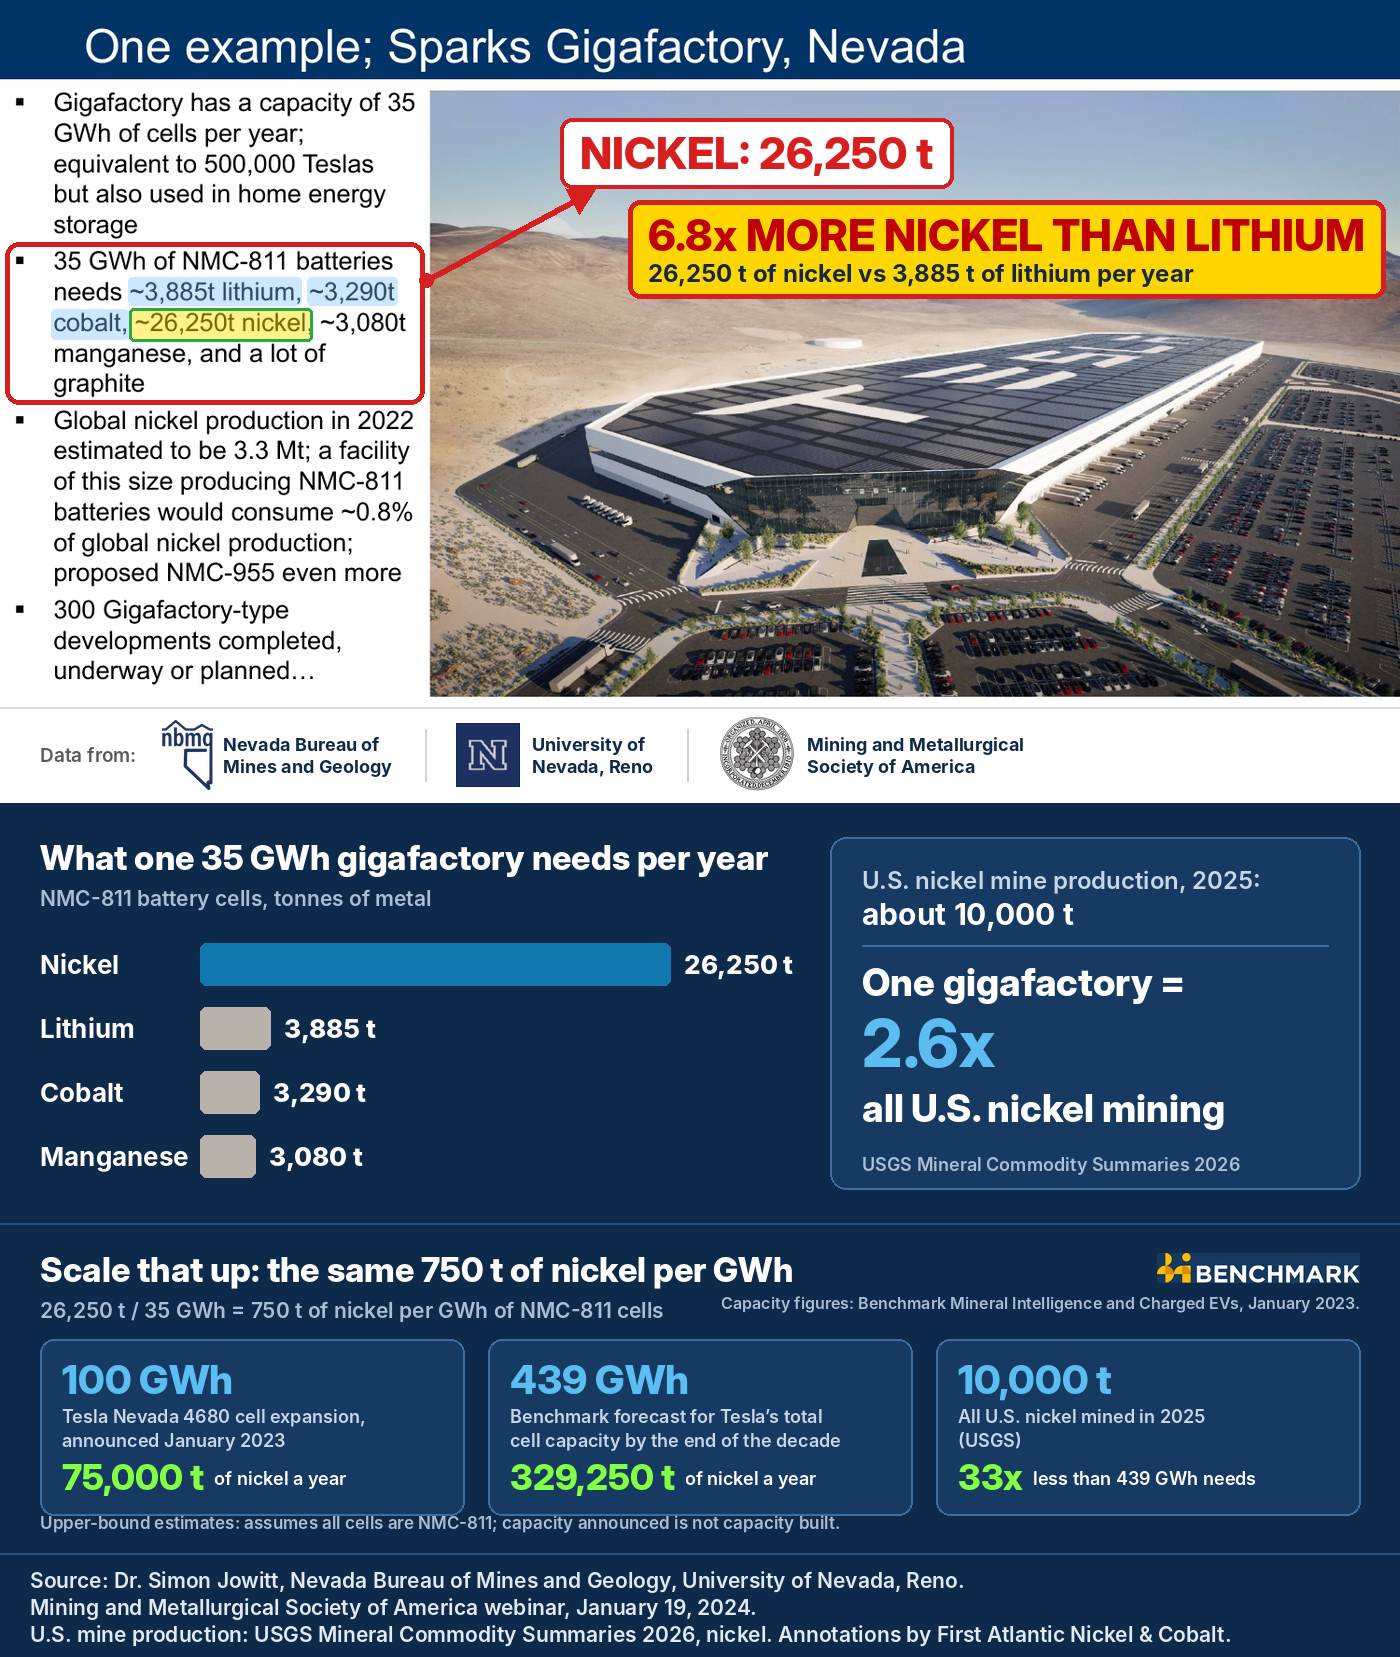
How much nickel does one gigafactory use? A 35 GWh plant, cells for about 500,000 Teslas a year, needs roughly 26,250 tonnes of nickel, close to 1% of world output, and some 300 such projects are built, under way or planned.[104] Japan targets 150 GWh by 2030,[106] and North America’s build-out has no smelter-free nickel source behind it.[104]
Click the figure for a larger, high-resolution view
+ More about this figure− Less
Click the figure for a larger, high-resolution view
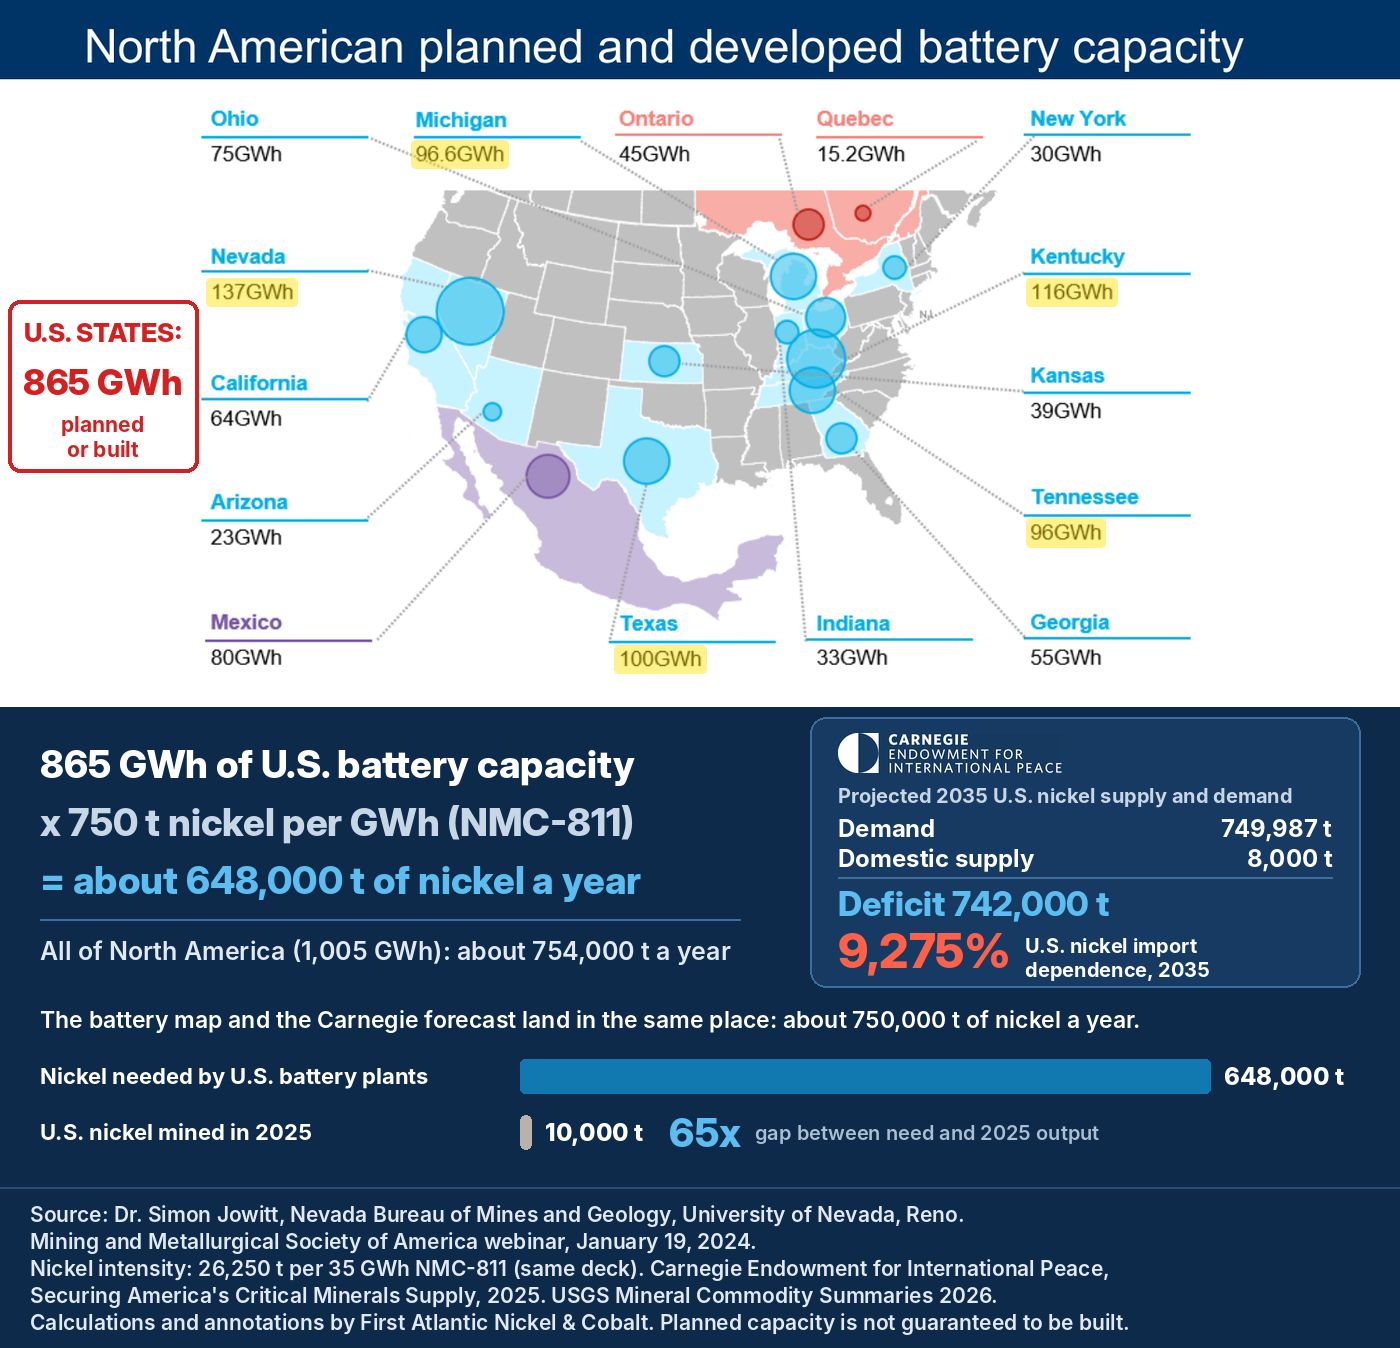
+ More about this figure− Less
Nickel and cobalt in one alloy, from Canada, with no smelter: that is what Pipestone XL brings to that market.
Newfoundland and Labrador: Canada’s Fastest-Growing Province, Quick Permitting, Churchill Falls Power and an Atlantic Deep-Water Port
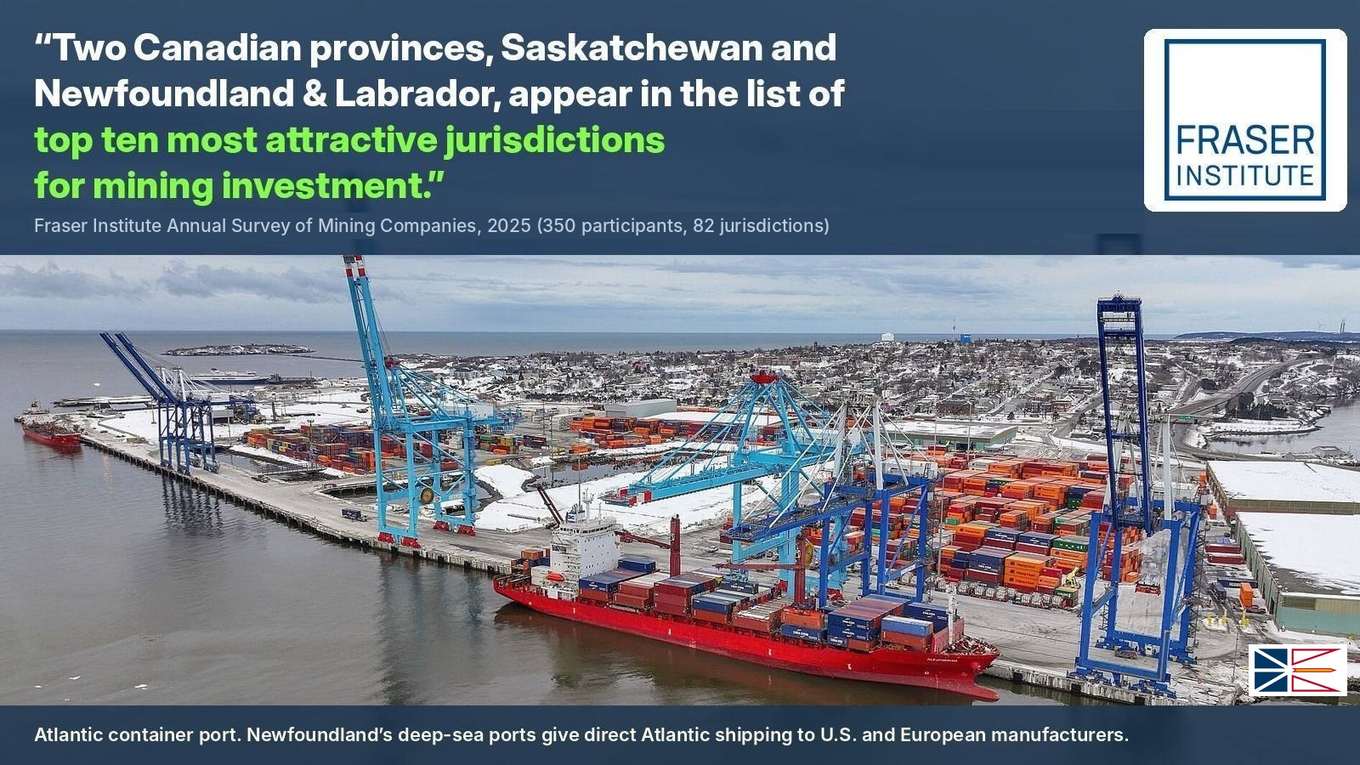
+ More about this figure− Less
Pipestone XL lies within about 200 km of an international airport and Vale’s Long Harbour nickel plant, with highway access.[5][110] Hydro rates are among the cheapest in North America, and the Fraser Institute ranks the province 7th in the world on mining policy.[111]
The province is leading the country through the trade dispute. RBC and the provincial budget rank Newfoundland and Labrador first for growth in 2025 and 2026,[112][113] with record exploration spending forecast for 2026.[113]
Permitting is the province’s selling point. In August 2026 mines minister Lloyd Parrott also became Minister of Red Tape Reduction,[114] and on September 8 the province signed a “one project, one review” agreement with Ottawa.[115] Valentine Gold is the proof: registered in April 2019, approved by August 2022, with first gold on September 14, 2025.[116][117][118][119][120] About three years to permit and three to build.
Power is being secured too. The August 17, 2026 Churchill Falls and Gull Island agreement would keep a large block of hydro power in the province for industry;[121][122] it passed the House of Assembly on September 18 but is not yet binding.[123][124] Pipestone XL does not wait on it: 230 kV lines carrying Bay d’Espoir hydro power already pass near the project.
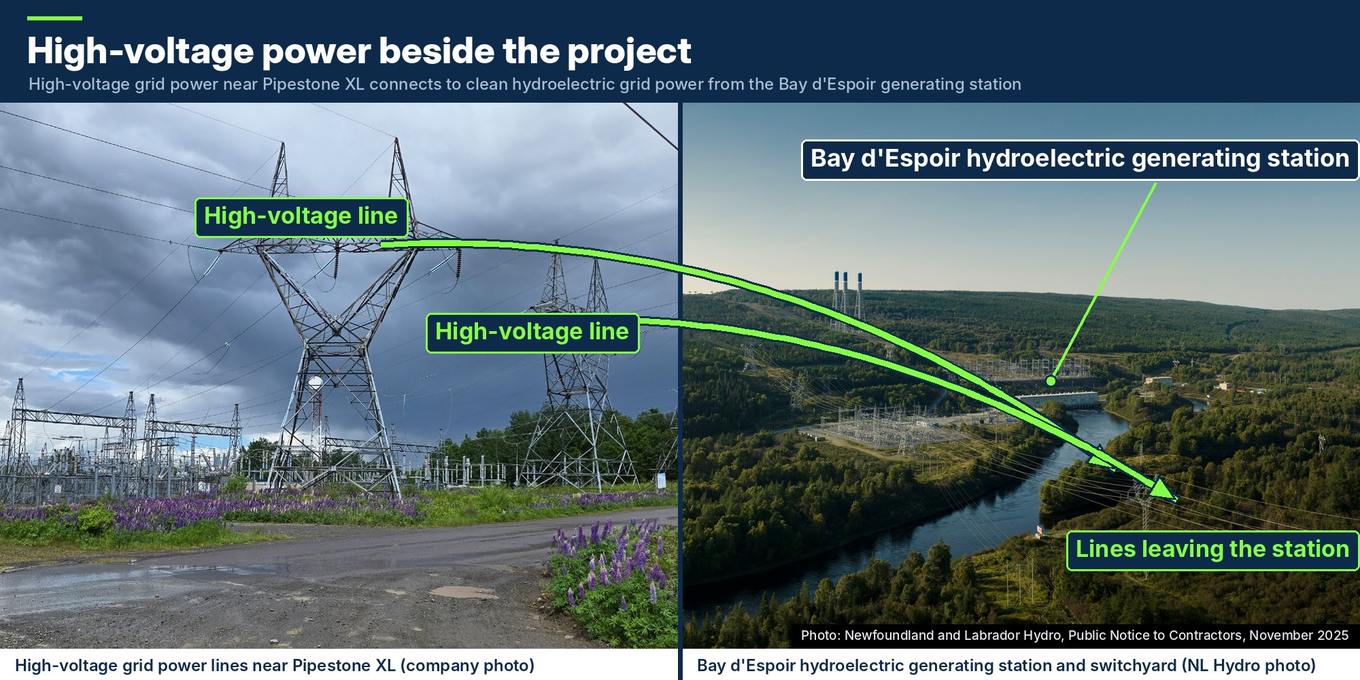
+ More about this figure− Less
The province has hosted a major nickel-cobalt discovery before, Voisey’s Bay,[15] and in 2022 Tesla signed for Vale’s Voisey’s Bay nickel.[125] That is history, not a forecast for Pipestone XL.
Management, Advisors and Funding: A P.Geo. CEO, Former Commerce and ARPA-E Officials and $13.4 Million Raised Since September
“North America has limited smelting capacity to meet future nickel and cobalt demand. Pipestone XL is a significant, large-scale ophiolite complex approximately 30 kilometres long, where awaruite occurs disseminated in the ultramafic host rock over large areas. It has the potential to be a large source of both metals without smelting, moving directly into downstream refining and bypassing that midstream processing constraint.”[5]
Adrian Smith, P.Geo., Chief Executive Officer and director, brings 15 years in mining and exploration, including a discovery taken to more than 7 billion tonnes in two years and two recent porphyry discoveries in British Columbia. B.Sc. Geology, Simon Fraser University.[126]
Former Director, Office of Critical Minerals and Metals, U.S. Department of Commerce
Former Program Director, ARPA-E, U.S. Department of Energy
Gary Stanley, Senior Strategic Advisor, former Director of the Office of Critical Minerals and Metals at the U.S. Department of Commerce, lead author of the 2019 Federal Critical Mineral Strategy.[39]
Dr. Douglas Wicks, Strategic Advisor, former ARPA-E Program Director at the U.S. Department of Energy, where he led the MINER program and geologic hydrogen work.[127]
Funding. About $13.4 million raised since September 2026, with no warrants.[5]
How to Invest Early in FAN: Three Ways to Follow First Atlantic Nickel & Cobalt and Pipestone XL
Large Nickel Discoveries Can Be Worth Billions of Dollars
What nickel discoveries have sold for. Four nickel acquisitions, as announced and in 2026 dollars, against First Atlantic’s market cap of about C$120 million. Each project differs, and past transactions are not a prediction of any future transaction or of First Atlantic’s value.
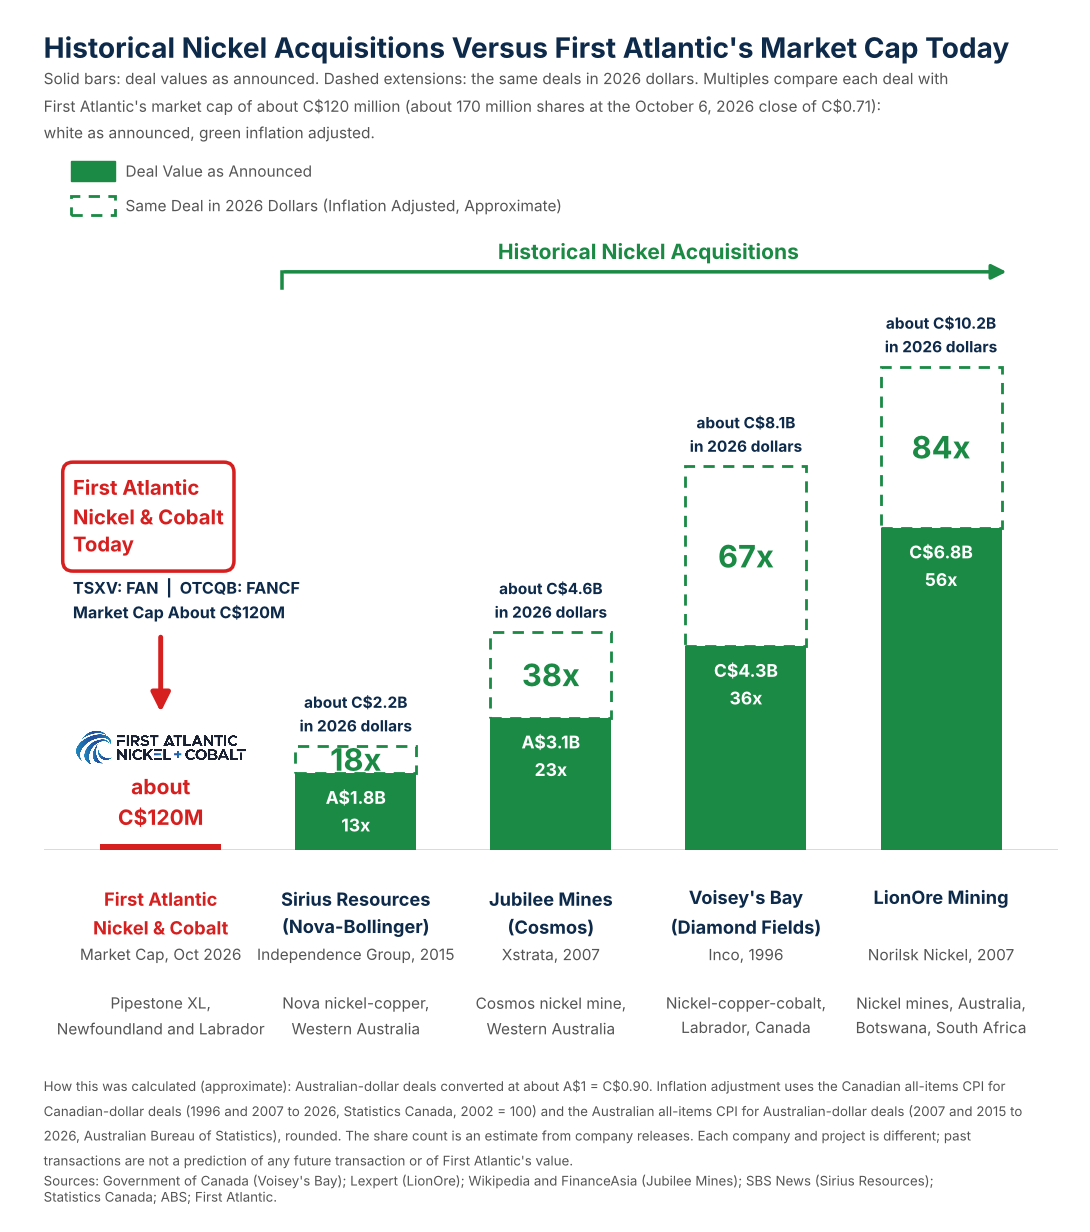
+ More about this figure− Less
Look up FAN at your broker.
First Atlantic trades in Canada on the TSX Venture Exchange under FAN and in the United States on the OTCQB under FANCF. Search the symbol at TD Direct Investing, RBC Direct Investing, Questrade, Wealthsimple, BMO InvestorLine, CIBC Investor’s Edge, Scotia iTRADE, Interactive Brokers or your own broker.
Add FAN to your watchlist.
Follow the share price and the news as XL-26-19 tests below the Alloy Max South discovery and bulk sample work advances at RPM.
Register for FAN news and investor updates.
Sign up below and news releases and investor updates come to you by email and text.
Remarks on Canada and the United States, critical minerals and the new economy
“On critical minerals, with rich endowments of potash, nickel, copper and uranium, Canada can be the most reliable supplier that America needs to put affordable food on the table, strengthen its national defence, and meet exploding demand to power AI.”[132]
Pipestone XL is a smelter-free Canadian source of nickel and cobalt in Newfoundland, held 100% by First Atlantic Nickel & Cobalt Corp. (TSX-V: FAN | OTCQB: FANCF).
Get FAN News and Investor Updates by Email and Text
Register once and every news release comes to you the day it is issued. You can stop the alerts at any time.
Follow Us on WhatsAppOfficial First Atlantic channel. One-way, your number stays private.Rob Guzman
Investor Relations, First Atlantic Nickel & Cobalt Corp.
1-844-592-6337 | rob@fanickel.com
Investor Relations: Robert Guzman | 1-844-592-6337 | ir@fanickel.com
First Atlantic Nickel & Cobalt Corp.
Suite 1890, 1075 West Georgia Street
Vancouver, British Columbia V6E 3C9, Canada
ir@fanickel.com
fanickel.com | News releases | Facebook | X | LinkedIn
Sources
- https://prod-natural-resources.azure.cloud.nrcan-rncan.gc.ca/minerals-mining/mining-data-statistics-analysis/minerals-metals-facts/nickel-facts
- https://finance.yahoo.com/quote/FAN.V/history/
- https://www.westmetall.com/en/markdaten.php?action=table&field=LME_Ni_cash
- https://finance.yahoo.com/quote/NIKL/history/
- https://fanickel.com/20261006-first-atlantic-nickel-cobalt-raises-total-of-13-4-million-with-additional-3-49-million-no-warrant-non-brokered-private-placement-at-0-83-per-share-a-premium-to-market-to-accelerate-exploration-at-pipestone-xl-nickel-cobalt-alloy-project
- https://www.canada.ca/en/natural-resources-canada/news/2026/04/one-year-of-nation-building-looking-back-moving-forward-keynote-address-by-minister-tim-hodgson.html
- https://www.glencore.com/what-we-do/metals-and-minerals/nickel/the-journey-of-nickel
- https://canadianminingjournal.com/news/nickel-potash-vale-to-close-thompson-smelter-stalls-kronau-project
- https://openparliament.ca/committees/international-trade/45-1/45/pierre-gratton-1/only/
- https://www.rbc.com/en/thought-leadership/energy/mine-refine-bridging-canadas-critical-minerals-capital-gap/
- https://fanickel.com/20260624-first-atlantic-nickel-cobalt-produces-high-grade-alloy-concentrate-up-to-71-9-nickel-and-1-76-cobalt-from-its-pipestone-xl-nickel-cobalt-alloy-project-using-its-first-ever-onshore-max-magnetic-alloy-extraction-recovery-concentration-process-unvei
- https://fanickel.com/20260521-first-atlantic-nickel-cobalt-reports-electron-microprobe-analysis-returning-77-62-nickel-and-1-69-cobalt-in-awaruite-at-the-rpm-zone-pipestone-xl-project-a-rare-naturally-magnetic-ni-fe-co-high-grade-alloy-mineralogically-capable-of-bypassing-mid
- https://fanickel.com/20260624-first-atlantic-nickel-cobalt-produces-high-grade-alloy-concentrate-up-to-71-9-nickel-and-1-76-cobalt-from-its-pipestone-xl-nickel-cobalt-alloy-project-using-its-first-ever-onshore-max-magnetic-alloy-extraction-recovery-concentration-process-unvei
- https://fanickel.com/20261013-first-atlantic-nickel-cobalt-drills-first-discovery-hole-at-alloy-max-south-zone-with-drill-hole-xl-26-18-best-near-surface-visible-awaruite-to-date-at-alloy-max-ending-in-open-mineralization-xl-26-17-extends-alloy-max-north-drilling-now-spans-2-
- https://publications.gc.ca/Pilot/LoPBdP/BP/bp422-e.htm
- https://fanickel.com/20260127-first-atlantic-nickel-increases-rpm-zone-strike-length-50-to-over-1-2-km-and-width-to-over-800-m-from-phase-2x-drilling-at-pipestone-xl-magnetic-nickel-cobalt-alloy-project
- https://www.canada.ca/content/dam/nrcan-rncan/documents/critical-minerals-discussion-paper-eng-2.pdf
- https://www.canada.ca/en/campaign/critical-minerals-in-canada/critical-minerals-an-opportunity-for-canada
- https://www.govinfo.gov/content/pkg/FR-2025-06-09/html/2025-10524.htm
- https://www.thompsoncoburn.com/insights/trump-administration-issues-proclamation-imposing-50-section-232-tariffs-export-controls-on-some-copper-scrap/
- https://www.federalregister.gov/documents/2026/01/20/2026-01045/adjusting-imports-of-processed-critical-minerals-and-their-derivative-products-into-the-united
- https://pubs.usgs.gov/periodicals/mcs2026/mcs2026-nickel.pdf
- https://www.canada.ca/en/intergovernmental-affairs/news/2025/06/implementation-of-bill-c-5-one-canadian-economy.html
- https://www.mining.com/?p=1200797
- https://www.fraserinstitute.org/commentary/newfoundland-government-should-help-make-mining-sector-more-attractive-investment
- https://www.cbc.ca/news/canada/manitoba/thompson-refinery-shutting-down-1.896396
- https://canadianminingjournal.com/news/nickel-ceremony-opens-vales-long-harbour-hydromet-plant
- https://theglobeandmail.com/business/article-canada-nickel-co-introduces-plans-for-new-processing-facilities-but/
- https://www.canada.ca/en/natural-resources-canada/news/2026/03/the-honourable-tim-hodgson-minister-of-energy-and-natural-resources-canadas-mining-moment-prosperity-security-and-sustainability-invest-in-canada-d.html
- https://fanickel.com/20260619-first-atlantic-nickel-cobalt-highlights-g7-leaders-declaration-on-critical-minerals-g7-names-nickel-one-of-only-two-pilot-minerals-for-a-new-allied-traceability-framework-moves-to-mobilize-equity-investment-and-offtake-and-establishes-a-critical-
- https://www.mining.com/web/canada-japan-consider-critical-minerals-joint-stockpiling-in-hunt-for-china-alternatives/
- https://www.canada.ca/en/natural-resources-canada/news/2026/06/canada-and-the-republic-of-korea-deepen-co-operation-on-energy-resources-and-critical-minerals.html
- https://www.ourcommons.ca/documentviewer/en/45-1/NDDN/meeting-26/evidence
- https://d9-wret.s3.us-west-2.amazonaws.com/assets/palladium/production/mineral-pubs/nickel/mcs-2012-nicke.pdf
- https://fanickel.com/20260427-first-atlantic-nickel-announces-name-change-to-first-atlantic-nickel--cobalt-ahead-of-the-washington-dc-safe-summit-reinforcing-the-natural-cobalt-content-of-awaruite---a-rare-naturally-magnetic-ni-fe-co-alloy-that-is-sulfur-free-and-can-bypass-m
- https://occ.ca/wp-content/uploads/Beneath_the_Surface_web-1.pdf
- https://youngkim.house.gov/2026/06/08/reps-kim-bera-dominance-act-passes-u-s-house-of-representatives/
- https://fanickel.com/20260611-first-atlantic-highlights-u-s-dominance-act-passed-by-house-new-critical-minerals-bill-authorizes-equity-investment-co-financing-and-u-s-priority-offtake-for-allied-projects-and-defines-processed-as-a-metal-metal-powder-or-a-master-alloy-awaruite
- https://fanickel.com/20260630-first-atlantic-nickel-cobalt-welcomes-former-director-of-the-office-of-critical-minerals-and-metals-at-the-united-states-department-of-commerce-gary-stanley-as-senior-strategic-advisor
- https://www.gov.mb.ca/sd/eal/registries/557.1/notice_of_alteration_smelter_refinery_closure_final.pdf
- https://transitionaccelerator.ca/wp-content/uploads/2025/08/From-Rocks-to-Power-Nickel.pdf
- https://www.cgai.ca/building_supply_chain_resiliency_of_critical_minerals
- https://www.clevelandcliffs.com/news/news-releases/detail/417/cliffs-natural-resources-releases-northern-ontario-chromite
- https://northernontariobusiness.com/industry-news/mining/province-offered-cliffs-special-power-deal-370067
- https://www.cbc.ca/lite/story/1.2434628
- https://www.sootoday.com/local-news/smelter-wont-go-where-its-not-wanted-noront-784867
- https://northernontario.ctvnews.ca/ring-of-fire-smelter-to-be-built-in-sault-ste-marie-1.4411525
- https://ero.ontario.ca/notice/026-0853
- https://news.hydroquebec.com/news/press-releases/all-quebec/hydro-quebec-proposing-regie-energie-new-rate-large-data-centres-adjustment-rate-cryptographic-use-applied-blockchains.html
- https://www.mining.com/web/column-power-trumps-tariffs-as-another-us-aluminum-smelter-shuts/
- https://occ.ca/wp-content/uploads/ReportCardonRingofFire-1.pdf
- https://ero.ontario.ca/notice/013-0903
- https://vale.com/documents/d/guest/2023-vale-community-engagement-report-31-march-2024
- https://ero.ontario.ca/notice/019-1107
- https://www.cbc.ca/news/canada/sudbury/sulphur-dioxide-emission-limits-sudbury-mining-smelters-1.4590260
- https://www.glencore.ca/en/media-and-insights/insights/process-gas-project-delivering-environmental-sustainability
- https://www.canada.ca/en/environment-climate-change/services/canadian-environmental-protection-act-registry/publications/code-practice-base-metals-smelters/summary.html
- https://www.winnipegfreepress.com/business/2010/11/18/smelter-refinery-called-unfeasible
- https://www.clevelandcliffs.com/news/news-releases/detail/382/cliffs-natural-resources-inc-announces-2012-capital
- https://www.ourcommons.ca/DocumentViewer/en/45-1/NDDN/meeting-25/evidence
- https://www.oregon.gov/dogami/milo/archive/MiningDistricts/DouglasCounty/RiddleDistrict/HannaNickelMine/HannaNickelMineNews.pdf
- https://www.bpa.gov/-/media/Aep/about/publications/records-of-decision/1983-rod/rod-19830929-1983-final-rate-proposal.pdf
- https://www.osti.gov/biblio/5675888
- https://www.law.cornell.edu/uscode/text/16/839e
- https://d9-wret.s3.us-west-2.amazonaws.com/assets/palladium/production/mineral-pubs/nickel/500498.pdf
- https://www.permits.performance.gov/permitting-project/fast-41-covered-projects/project-crucible
- https://investors.koreazinc.co.kr/media/z1pp5yu3/korea-zinc-us-smelter-investment-english.pdf
- https://www.theinvestor.co.kr/article/10639449
- https://www.cia.gov/readingroom/document/cia-rdp64b00346r000100170001-6
- https://oregonnews.uoregon.edu/lccn/sn85042472/1962-08-16/ed-1/seq-3/
- https://oregonnews.uoregon.edu/lccn/sn85042472/1962-10-08/ed-1/seq-14/
- https://www.ourcommons.ca/documentviewer/en/45-1/NDDN/meeting-25/evidence
- https://www.fanickel.com/20241029-first-atlantic-nickel-drills-wide-interval-of-visible-disseminated-awaruite-nickel-at-super-gulp-target-new-discovery-16-km-south-of-historical-drilling-at-atlantic-lake
- https://fanickel.com/20260716-first-atlantic-nickel-cobalt-expands-alloy-max-zone-445-meters-south-of-the-discovery-hole-xl-26-16-the-deepest-hole-to-date-at-pipestone-xl-intersects-large-grain-visible-awaruite-ni-fe-co-alloy-over-its-entire-525-meter-length-ending-in-open-mi
- https://fanickel.com/20250813-first-atlantic-nickel-reports-initial-phase-2-drill-results-deepest-drill-hole-to-date-at-rpm-zone-returns-1-27-awaruite-nickel-alloy-nife-in-magnetic-concentrate-over-447-meters
- https://fanickel.com/20250313-first-atlantic-nickel-releases-initial-dtr-metallurgical-results-magnetic-concentrate-of-1-37-nickel--1-73-chromium-over383-1metres
- https://fanickel.com/20260318-first-atlantic-nickel-announces-new-alloy-max-zone-discovery---a-second-large-scale-awaruite-nife-target-area-extending-7-km-north-from-the-rpm-zone-at-the-pipestone-xl-nickel-cobalt-alloy-project
- https://fanickel.com/20260615-first-atlantic-nickel-drills-second-large-scale-awaruite-ni-fe-co-alloy-discovery-at-alloy-max-north-pipestone-xl-project-5-2-km-north-of-rpm-zone-visible-awaruite-over-414-meter-drill-hole-ending-in-open-mineralization
- https://fanickel.com/20251211-first-atlantic-nickel-acquires-ophiolite-x-project-targeting-white-and-orange-geologic-hydrogen-carbon-capture-and-critical-minerals-in-westernnewfoundland
- https://fanickel.com/20260608-vema-hydrogen-and-first-atlantic-nickel-cobalt-sign-loi-to-develop-engineered-mineral-hydrogen-at-pipestone-xl-awaruite-project-in-newfoundland
- https://www.mdpi.com/2075-163X/13/3/440
- https://canadianminingjournal.com/news/chromite-noront-files-updated-43-101-for-three-ring-of-fire-deposits
- https://pubs.usgs.gov/periodicals/mcs2026/mcs2026-chromium.pdf
- https://www.imf.org/-/media/files/publications/wp/2021/english/wpiea2021243-print-pdf.pdf
- https://www.mining.com/hundreds-of-new-mines-required-to-meet-2030-battery-metals-demand-iea-report/
- https://www.csis.org/analysis/trade-critical-supply-chains
- https://carnegieendowment.org/research/2025/10/securing-americas-critical-minerals-supply
- https://globalvoices.org/2025/04/07/how-chinas-investment-in-indonesias-nickel-industry-is-impacting-local-communities/
- https://www.goldmansachs.com/insights/pages/gs-research/nickels-class-divide/report.pdf
- https://globalwitness.org/en/press-releases/europe-allowing-russian-mined-nickel-to-enter-western-markets/
- https://single-market-economy.ec.europa.eu/sectors/raw-materials/areas-specific-interest/critical-raw-materials/critical-raw-materials-act_en
- https://xml.metalbulletin.com/Article/5119706/flat-products-all/EU-outlines-copper-and-battery-grade-nickel-as-strategic-raw-materials-in-CRMA.html
- https://prod-natural-resources.azure.cloud.nrcan-rncan.gc.ca/minerals-mining/mining-data-statistics-analysis/minerals-metals-facts/cobalt-facts
- https://www.whitehouse.gov/presidential-actions/2026/01/adjusting-imports-of-processed-critical-minerals-and-their-derivative-products-into-the-united-states/
- https://decode39.com/15263/from-rome-to-evian-critical-minerals-become-part-of-italys-strategic-diplomacy/
- https://www.ourcommons.ca/documentviewer/en/45-1/NDDN/report-4
- https://www.scotiabank.com/content/dam/scotiabank/canada/scotia-growth-institute/files/english/The_World_Needs_More_Canada_Critical_Minerals_Mining_Capabilities.pdf
- https://www.pm.gc.ca/en/news/news-releases/2026/06/17/prime-minister-carney-secures-new-partnerships-defence-and-critical
- https://www.canada.ca/en/campaign/critical-minerals-in-canada/our-critical-minerals-strategic-partnerships/joint-statement-of-intent-between-canada-and-the-united-kingdom-on-collaboration-on-critical-minerals.html
- https://www.miningweekly.com/article/samsung-sdi-invests-in-canada-nickel-2024-01-15
- https://resourceworld.com/sumitomo-invests-14-4-million-for-9-9-stake-in-fpx-nickel/
- https://www.brookings.edu/wp-content/uploads/2022/08/LTRC_ChinaSupplyChain.pdf
- https://portofargentia.ca/about/
- https://mmsa.net/wp-content/uploads/2024/01/Jowitt-MMSA-Webinar-January-2023-v2_nohide.pdf
- https://transportandenergy.com/2025/07/22/30-gigafactories-now-operational-in-europe
- https://www.gtai.de/de/trade/japan/branchen/japan-foerdert-den-bau-weiterer-batteriewerke-fuer-elektroautos-1818898
- https://source.benchmarkminerals.com/article/tesla-takes-on-byds-crown-with-100-gwh-nevada-expansion
- https://chargedevs.com/newswire/tesla-to-build-semis-and-expand-battery-production-at-nevada-gigafactory/
- https://www.fraserinstitute.org/studies/annual-survey-mining-companies-2024
- https://fanickel.com/20260408-first-atlantic-nickel-commences-drilling-at-new-alloy-max-zone-discovery-7-km-north-of-rpm-zone-at-the-pipestone-xl-nickel-cobalt-alloy-project
- https://www.fraserinstitute.org/sites/default/files/2026-02/annual-survey-of-mining-companies-2025.pdf
- https://www.rbc.com/en/economics/wp-content/uploads/sites/23/2026/09/Provincial-forecast-tables-Q3-2026-RBC-Economics.pdf
- https://www.gov.nl.ca/budget/2026/wp-content/uploads/sites/10/Budget-2026-The-Economy.pdf
- https://www.gov.nl.ca/releases/2026/exec/0820n02/
- https://www.gov.nl.ca/releases/2026/eccc/0908n07/
- https://www.gov.nl.ca/releases/2019/mae/0416n09/
- https://www.gov.nl.ca/releases/?p=38587
- https://www.kitco.com/news/article/2022-08-25/marathon-announces-completion-federal-enviro-assessment-valentine-gold
- https://www.globenewswire.com/news-release/2022/09/01/2508380/0/en/Marathon-Makes-Construction-Decision-for-the-Valentine-Gold-Project-and-Provides-Project-Development-Update.html
- https://www.newsfilecorp.com/release/266379/Equinox-Gold-Delivers-First-Gold-at-its-Valentine-Gold-Mine-in-Newfoundland-and-Labrador-Canada
- https://www.gov.nl.ca/releases/2026/exec/0817n01/
- https://www.pm.gc.ca/en/node/53643
- https://www.bnnbloomberg.ca/business/politics/2026/09/18/newfoundland-and-labrador-votes-in-favour-of-quebec-energy-agreement-worth-billions/
- https://ntv.ca/news/sovereigntist-parti-quebecois-wins-quebec-election-as-n-l-waits-to-see-what-happens-next-with-churchill-falls-deal/
- https://vale.com/w/vale-confirms-supply-deal-with-tesla-for-low-carbon-nickel
- https://www.fanickel.com/
- https://fanickel.com/20260429-first-atlantic-nickel--cobalt-welcomes-dr--douglas-wicks-former-program-director-for-the-u-s--department-of-energys-arpa-e-advanced-research-projects-agency-energy-miner-program-and-geologic-hydrogen-portfolio-as-strategic-advisor
- https://www.lexpert.ca/big-deals/norilsk-nickel-acquires-lionore-mining-for-68b/346316
- https://en.wikipedia.org/wiki/Cosmos_Nickel_Mine
- https://www.sbs.com.au/news/article/wa-miners-in-1-8b-takeover-deal/uxvrrzuy3
- https://www150.statcan.gc.ca/n1/pub/62-001-x/2016007/t040-eng.htm
- https://www.pm.gc.ca/en/news/speeches/2026/05/28/prime-minister-carney-delivers-remarks-economic-club-new-york
Disclaimer
This webpage has been prepared and distributed by First Atlantic Nickel & Cobalt Corp. and constitutes a promotional communication. It is provided for informational purposes only and does not constitute financial or investment advice or a recommendation, offer or solicitation to buy or sell any securities. Investing in securities involves risk, including the risk of loss of principal. Past performance is not indicative of future results, and no assurance can be given that any objectives, projections or expectations described on this page will be achieved. Market forecasts cited on this page are third-party views and are inherently uncertain; actual price and demand outcomes may differ materially.
No securities regulator or stock exchange has reviewed or accepts responsibility for its contents. Recipients should conduct their own research and consult qualified investment professionals before making any investment decisions. By reading this communication, you acknowledge and agree that neither First Atlantic Nickel & Cobalt Corp. nor any of its directors, officers, employees, agents, or promoters accepts any liability for any direct or consequential loss or damages arising from reliance on the information contained herein.
Scientific and Technical Information
The scientific and technical information on this page has been reviewed and approved by Adrian Smith, director and the Chief Executive Officer of the Company whom is a qualified person as defined by NI 43-101. The qualified person is a member in good standing of the Professional Engineers and Geoscientists Newfoundland and Labrador (PEGNL) and is a registered professional geoscientist (P.Geo.). Unless otherwise indicated, the technical information on this page is derived from the Company's previously filed disclosure, including news releases available under the Company's profile on SEDAR+.
Forward-Looking Information
This page contains "forward-looking information" within the meaning of applicable Canadian securities laws, including, without limitation, statements regarding: anticipated North American and U.S. demand for nickel, cobalt and chromium; projected supply deficits, import dependence and price trends; the potential strategic importance of the Pipestone XL Project; the potential for awaruite mineralization to support smelter-free or onshore processing; the potential ability of concentrate from the Project to be processed by downstream North American customers; expected metallurgical, recovery, concentrate grade, by-product and processing outcomes; the extent, scale and continuity of mineralization; future exploration, drilling, metallurgical testing and development plans; the ONSHORE MAX™ process and the planned bulk sample; the construction, timing and benefits of the District Road; the use and sufficiency of the proceeds of the 2026 financings and the qualification of expenditures as Canadian exploration expenses; potential benefits from government policies or programs; permitting, environmental, infrastructure and timeline advantages; and potential opportunities relating to chromium, geologic hydrogen and carbon capture. Forward-looking information is often, but not always, identified by words such as "expects," "plans," "targets," "believes," "projects," "potential," "could," "may," "will," "anticipates," and similar expressions.
Forward-looking information on this page is based on a number of material factors and assumptions, including, among other things: the accuracy of current geological, geophysical, geochemical, drilling, sampling, assay and metallurgical data interpretations; the continuation of observed mineralization and metallurgical characteristics; the ability to obtain results from additional drilling and testing consistent with results to date; the availability of financing, personnel, equipment and contractor support; the timely receipt of permits, approvals and access; that exploration and road construction proceed as planned and that expenditures qualify as Canadian exploration expenses; the availability of infrastructure, processing, refining and transportation alternatives; the continuation of supportive critical mineral, trade and industrial policies in Canada and the United States; and management's current expectations regarding market conditions, demand, pricing and supply chain dynamics for nickel, cobalt and chromium.
Forward-looking information is subject to known and unknown risks, uncertainties and other factors that may cause actual results or events to differ materially from those expressed or implied by such forward-looking information. These include, without limitation: exploration results not supporting current interpretations; drilling, sampling, assay, metallurgical or recovery results that differ from results obtained to date; the absence of a mineral resource estimate or economic study demonstrating economic viability; changes in commodity prices, demand forecasts, tariffs, quotas, trade measures or critical mineral policies; the inability to secure financing, permits, social licence, infrastructure, contractors, processing arrangements or offtake relationships on acceptable terms or at all; technical, engineering, processing, scale-up or recovery challenges, including bench-scale metallurgical results not being achievable at larger scales; visual observations of mineralization not being confirmed by assays; cost inflation; environmental and regulatory risks; title, access, weather and operational risks; and general economic, market and capital markets conditions. Readers are cautioned that actual results may differ materially from the forward-looking information on this page, and undue reliance should not be placed on such information.
The forward-looking information on this page is given as of November 2026, and First Atlantic Nickel & Cobalt Corp. undertakes no obligation to update or revise such information except as required by applicable securities laws.
Readers should review the Company's continuous disclosure filings available on SEDAR+ at www.sedarplus.ca and should conduct their own independent review before making any investment decision.
© 2026 First Atlantic Nickel & Cobalt Corp. | TSX-V: FAN | OTCQB: FANCF | FSE: P210
First Atlantic Nickel & Cobalt Corp., Suite 1890, 1075 West Georgia Street, Vancouver, British Columbia V6E 3C9, Canada. Investor Relations: 1-844-592-6337, ir@fanickel.com.